Round Rock, TX · $1.85M
Purpose-built 9,400 SF center, 8 classrooms, fenced playground and drop-off lane
Year-1 federal benefit
$360,000
A licensed center is not a plain office. The state tells you to build a secure entry, a hand-wash station in every classroom, a kitchen and a fenced playground — and almost none of that belongs on the 39-year schedule.
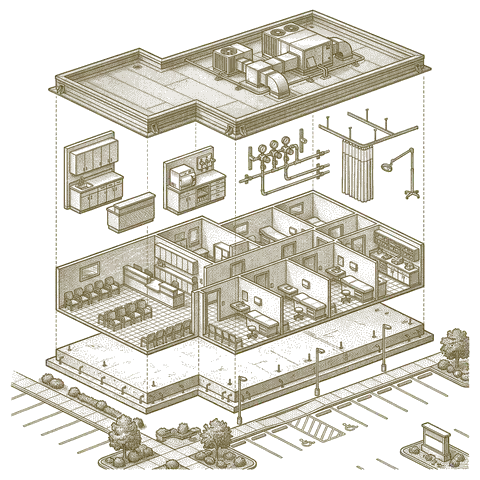
Child day care cost segregation is an engineering-based study that reclassifies a licensed child care center or preschool's components out of the 39-year commercial building schedule into faster 5-, 7- and 15-year MACRS classes. Child day care is asset class 57.0, distributive trades and services, under Rev. Proc. 87-56, so qualifying personal property in the building is 5-year. What moves is largely what the licensing rules required: the secure entry vestibule's access control, the per-classroom hand-wash and diaper-changing casework, classroom cubbies and cot storage, classroom carpet and cushioned flooring, child-safety gates and dividers, the commercial kitchen's equipment and the dedicated plumbing, gas and hood exhaust serving it, the laundry connections, security cameras and low-voltage cabling, and removable wall protection and themed graphics. The fenced playground is the other half: safety surfacing, play structures, fencing and the parent drop-off lane are 15-year land improvements. The shell, roof, comfort HVAC, restroom plumbing including child-height fixtures, and general lighting stay 39-year. A center typically reclassifies 15–28% of basis, with a purpose-built center near the top and a converted house or strip-retail bay near the floor.
Child day care cost segregation reclassifies 15–28% of depreciable basis from the 27.5- or 39-year shell into 5-, 7-, and 15-year MACRS classes per 26 U.S.C. § 168 and Rev. Proc. 87-56. Under OBBBA's permanent 100% bonus depreciation (placed-in-service 2025+), reclassified components are deductible in year one. All credible cost-seg providers use the same federal framework — industry-standard 2026 construction cost data, MACRS classification, IRS Audit Techniques Guide (Pub 5653) compliance. What differs across property types is land-allocation share, FF&E weight, and material-participation eligibility under §469.
| Property type | Reclass to 5/7/15-yr | Year-1 federal benefit | Study cost |
|---|---|---|---|
| STR | 20–39% | $48K–$280K | From $495 |
| SFR | 8–32% | $16K–$165K | From $495 |
| Condo | 10–17% | $16K–$61K | From $495 |
| Brownstone | 5–20% | $60K–$640K | From $495 |
| Rowhouse | 5–18% | $10K–$170K | From $495 |
| Duplex | 13–21% | $31K–$105K | From $995 |
| Fourplex | 16–29% | $64K–$230K | From $995 |
| Office | 16–29% | $84K–$650K | From $1,995 |
| Retail | 20–37% | $90K–$690K | From $1,995 |
| Industrial | 15–28% | $78K–$840K | From $2,495 |
| Self-storage | 19–36% | $140K–$1.6M | From $2,495 |
| Medical office | 16–29% | $84K–$540K | From $2,995 |
| Mixed-use | 12–23% | $63K–$515K | From $1,995 |
| Multifamily | 15–28% | $48K–$200K | From $995 |
| Multifamily 5+ | 14–26% | $110K–$1.0M | From $1,995 |
| Triplex | 14–26% | $44K–$165K | From $995 |
| Restaurant | 16–29% | $72K–$430K | From $2,995 |
| Vet | 19–36% | $85K–$540K | From $2,995 |
| Gym | 21–40% | $110K–$900K | From $2,995 |
| Dealership | 25–47% | $465K–$4.2M | From $2,995 |
| ADU | 7–14% | $8K–$39K | From $495 |
| Commercial | 18–34% | $94K–$765K | From $1,995 |
| Data center | 43–65% | $2.5M–$29M | $4,995–$54,995 (sub-$100M); $100M+ by proposal |
| Senior living | 21–39% | $315K–$2.3M | By proposal |
| Funeral homes | 18–30% | $135K–$900K | By proposal |
| Child day care this page | 15–28% | $56K–$630K | From $2,995 |
| Adult day care | 14–26% | $78K–$780K | From $2,995 |
| Church | 10–22% | $37K–$825K | From $2,995 |
Reclassification ranges from internal benchmarks across 4,000+ studies; Year-1 federal benefit assumes 37% bracket and full first-year usability. Study costs are Cost Seg Smart pricing — comparable engineering studies elsewhere range $5,000–$15,000+. See full provider comparison.
Estimates assume 37% federal bracket and full first-year usability of the loss (active income offset or REPS). Your actual benefit varies with bracket, basis allocation, and CPA's treatment.
Pre-set to Child day care defaults — adjust price + bracket to match your property.
Yes. A licensed center is nonresidential real property on the 39-year schedule, and a study moves the parts of it that are personal property or land improvements onto 5-, 7- and 15-year schedules. Child day care is asset class 57.0, distributive trades and services, under Rev. Proc. 87-56, so qualifying personal property in the building is 5-year. An estimated 15–28% of basis reclassifies, on the facts of the specific center.
Because licensing makes you build things an office does not have. A secure entry vestibule with keypad, buzzer release and intercom; a hand-wash station and a diaper-changing counter in every room that takes infants and toddlers; a commercial kitchen with its own gas, plumbing and hood exhaust because the center serves meals; a laundry for bedding and bibs; cameras in every classroom. Those serve the care operation rather than the building, and they are the reason this type sits above office. The fenced outdoor play area adds the second lever, on the 15-year side.
Typically reclassified to 5-year: classroom cubbies, storage casework and cot or mat storage; diaper-changing stations and classroom hand-wash casework; classroom carpet tile and cushioned resilient flooring; removable acoustic panels; child-safety gates, half-doors and room dividers; indoor motor-room play equipment and padding; nap-room dimming controls; commercial kitchen equipment and the dedicated plumbing, gas and hood connections serving it; laundry connections; access control, cameras and low-voltage cabling; decorative and accent lighting; removable wall protection and themed graphics; interior signage. Fifteen-year land improvements: playground safety surfacing, play structures, perimeter fencing and gates, the parent drop-off lane, parking and striping, site lighting, landscaping and irrigation, sidewalks, stormwater detention and the monument sign. Stays 39-year: the shell and roof, interior partitions, comfort HVAC, sprinklers, restroom plumbing including child-height fixtures, glued-down sheet flooring in restrooms and the kitchen, and general lighting.
The building owner's. The landlord depreciates the building, the site work and anything that conveyed with the purchase, and that is the study this page describes. The operator depreciates its own furniture and equipment and any build-out the operator paid for — that is a leasehold improvement study on the operator's return, and it is a separate engagement. If you are the operator and you also bought the building, you get both, and the intake asks which equipment and furnishings were included in the purchase so the two do not overlap.
Often yes, but expect the low end of the band. A conversion usually keeps the residential shell, adds the licensing fixtures room by room, and sits on a small lot, so the 15-year site work that carries a purpose-built center is thin. That is exactly why the published floor is 15% rather than something rounder — the weakest real form of this type has to be inside the range we advertise.
The address, the purchase price and closing date, square footage, year built, the number of classrooms, and whether equipment or furnishings were included in the purchase. A closing statement, a rent roll or lease if the building is leased to an operator, and any construction or build-out invoices make the result sharper, and documented costs are used in place of modeled ones wherever you have them. Photos help. If the center was placed in service in a prior year, a Form 3115 lookback catches the missed depreciation in the current year without amending.
Drop your email and we'll unlock all sample reports — STR, SFR, multifamily, commercial, per-city. No spam, no nag.
One email unlocks every sample on the site. We use it to send the reports + an optional 5-day cost-seg primer (unsubscribe anytime).