Assisted living community · By proposal
Resident-room FF&E + dining + clinical MEP + amenity grounds
Year-1 federal benefit
Custom-scoped
A senior living community is a residential operating business — dense resident-room FF&E, hospitality common areas, clinical MEP, and large amenity grounds, all reclassifiable out of the long building life.
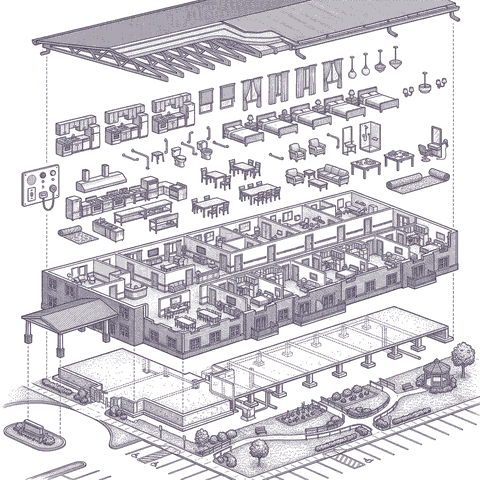
Senior living cost segregation is an engineering-based study that reclassifies an assisted-living, independent-living, memory-care, or skilled-nursing facility's components out of its default depreciation schedule into faster 5-, 7-, and 15-year MACRS classes. A senior living facility blends dense residential FF&E (resident-room furniture, appliances, casework, and finishes), hospitality-style common areas (dining, commercial kitchen, salon, therapy, and activity spaces), specialty and clinical MEP (nurse-call, emergency power, and medical gas where present), and substantial site work (parking, landscaping, and outdoor amenity areas), so it typically reclassifies 21–39% of basis. Because these are operating-business properties with complex ownership, senior living studies are scoped per engagement rather than self-served — contact us for a proposal.
Senior living cost segregation reclassifies 21–39% of depreciable basis from the 27.5- or 39-year shell into 5-, 7-, and 15-year MACRS classes per 26 U.S.C. § 168 and Rev. Proc. 87-56. Under OBBBA's permanent 100% bonus depreciation (placed-in-service 2025+), reclassified components are deductible in year one. All credible cost-seg providers use the same federal framework — public government construction cost data, MACRS classification, IRS Audit Techniques Guide (Pub 5653) compliance. What differs across property types is land-allocation share, FF&E weight, and material-participation eligibility under §469. For the general explanation, see what a cost segregation study is and what the report contains.
| Property type | Reclass to 5/7/15-yr | Year-1 federal benefit | Study cost |
|---|---|---|---|
| STR | 19–39% | $45K–$280K | From $495 |
| SFR | 8–32% | $16K–$165K | From $495 |
| Condo | 10–19% | $18K–$76K | From $495 |
| Brownstone | 5–20% | $60K–$640K | From $495 |
| Rowhouse | 5–18% | $10K–$170K | From $495 |
| Duplex | 8–21% | $19K–$105K | From $995 |
| Fourplex | 14–29% | $56K–$230K | From $995 |
| Office | 16–29% | $84K–$650K | From $995 |
| Retail | 20–37% | $90K–$690K | From $995 |
| Industrial | 15–28% | $78K–$840K | From $2,495 |
| Self-storage | 10–36% | $75K–$1.6M | From $2,495 |
| Medical office | 16–29% | $84K–$540K | From $2,995 |
| Mixed-use | 12–23% | $63K–$515K | From $995 |
| Multifamily | 14–28% | $44K–$200K | From $995 |
| Multifamily 5+ | 14–26% | $110K–$1.0M | From $1,995 |
| Triplex | 8–26% | $25K–$165K | From $995 |
| Restaurant | 16–29% | $72K–$430K | From $2,995 |
| Vet | 19–36% | $85K–$540K | From $2,995 |
| Gym | 21–40% | $110K–$900K | From $2,995 |
| Dealership | 25–47% | $465K–$4.2M | From $2,995 |
| ADU | 7–14% | $8K–$39K | From $495 |
| Commercial | 18–34% | $94K–$765K | From $995 |
| Data center | 43–65% | $2.5M–$29M | $4,995–$54,995 (sub-$100M); $100M+ by proposal |
| Senior living this page | 21–39% | $315K–$2.3M | By proposal |
| Funeral homes | 18–30% | $135K–$900K | By proposal |
| Child day care | 15–28% | $56K–$630K | From $2,995 |
| Adult day care | 14–26% | $78K–$780K | From $2,995 |
| Church | 10–22% | $37K–$825K | From $2,995 |
| Farm | 8–65%† | $19K–$780K | From $995 |
Reclassification ranges from the bands we publish per property type (measured on our delivered studies where we have enough of a type, modeled elsewhere); Year-1 federal benefit assumes 37% bracket and full first-year usability. Study costs are Cost Seg Smart pricing — comparable engineering studies elsewhere range $5,000–$15,000+. The ADU figure is an ADU acquired with a house; one the owner built or converted is priced on its documented construction cost, from $995. See full provider comparison.
† Farm: the figure is property with a recovery period of 20 years or less, on a farm with one or more rental houses on it. It counts 10- and 20-year property, which no other row has, and its dollar figure is a first-year deduction, not tax saved. A farm is quoted from a list of what is on it; see how.
A skilled nursing facility is usually nonresidential real property on the 39-year schedule. A cost segregation study separates the parts of it that serve patient care, the kitchen and laundry, the resident rooms and the grounds, and moves them into 5-, 7- and 15-year property that 100% bonus depreciation can deduct in the first year. Our modeled range for senior living and care facilities is 21–39% of depreciable basis. Clinical intensity and the size of the grounds move a facility within it. There is no published price for these studies. Each facility is scoped and quoted.
To use the 27.5-year residential schedule, at least 80% of a building's gross rental income has to come from dwelling units (IRC §168(e)(2)(A)). A skilled nursing facility is mostly paid for care, through Medicare and Medicaid per-diem rates and private pay, rather than rent for a dwelling. That is why most SNFs are depreciated as 39-year nonresidential property. Assisted and independent living depend more on the facts: where residents rent their apartment and care is billed separately, some owners are on the 27.5-year schedule. Your CPA makes that call. It changes the building's life, and it decides whether the interior-improvement rule below is available at all.
| Component | Usual class | Note |
|---|---|---|
| Nurse-call, resident-monitoring and wander-management systems | 5-year | Serve the care operation, not the building. |
| Commercial kitchen and laundry equipment, with the dedicated electrical, gas, water and exhaust serving it | 5-year | The equipment-serving share only. General building service stays with the building. |
| Resident-room furniture, casework, window treatments, removable flooring | 5-year | Heavier in rooms than in most commercial buildings. |
| Therapy and bathing-room equipment and its dedicated connections | 5-year | Fact-dependent, documented item by item. |
| Medical gas and emergency power | Reviewed case by case | Depends on whether the system serves equipment or the building's life-safety needs. |
| Parking, walkways, courtyards, secure gardens, fencing, site lighting, landscaping | 15-year | Land improvements. |
| Structure, roof, comfort HVAC, general lighting, sprinklers, elevators, restrooms | 39-year | Stays with the building. |
Separating equipment-serving systems from the building rests on Hospital Corporation of America v. Commissioner, 109 T.C. 21 (1997), a hospital case, along with Rev. Proc. 87-56, IRS Publication 946 and the Cost Segregation Audit Techniques Guide (Pub 5653).
Many nursing facilities are owned by one entity and leased, often triple-net, to an operator. The owner's study covers the building and the site. The operator can depreciate only what the operator paid for: its furniture and equipment, and any interior improvements it made after the building was placed in service. On a nonresidential building, those interior improvements can be qualified improvement property, which is 15-year and bonus-eligible under IRC §168(e)(6). Enlargements, elevators and escalators, and the internal structural framework do not qualify. A renovation of resident wings, dining or therapy space is often where the operator's deduction is.
A tax study changes your federal tax depreciation. It does not change the depreciation on your Medicare cost report, which follows CMS reimbursement rules rather than MACRS. Keep the two schedules separate, and tell whoever prepares the cost report that a tax study exists so nobody reconciles one to the other.
The study fits best in the year of acquisition, construction or a major renovation, when the closing statement or documented construction costs are fresh. Property both acquired and placed in service after January 19, 2025 qualifies for 100% bonus depreciation. A facility placed in service in an earlier year can take the missed depreciation in the current year through Form 3115, without amending prior returns.
These facilities are closer to apartments: more of the basis sits in resident units with their own kitchenettes, finishes and furniture, and in hospitality-style common areas like dining rooms, salons and activity space. Memory care adds secure courtyards and monitoring systems. The recovery-period question above decides the building schedule. The reclassification works the same way either way. An adult day centre, where nobody stays overnight, is a different property type: see adult day care cost segregation.
Pricing for these facilities: By proposal. We scope each one from its size and bed count, who owns the building and who owns the equipment, the documents available (closing statement, construction or renovation costs, fixed-asset ledger), and whether an on-site observation is needed. We include one by default at $3M or more of basis and whenever specialty clinical systems would change the component detail. The proposal states the fee, the scope and the delivery date before you commit.
To get a proposal, send: the facility address, licensed bed count, purchase or construction cost and date, whether you are the owner or the operator, and any fixed-asset or FF&E list you have.
Illustrative, modeled properties, not client engagements. Estimates assume 37% federal bracket and full first-year usability of the loss (active income offset or REPS). Your actual benefit varies with bracket, basis allocation, and CPA's treatment.
Yes. A senior living community blends dense resident-room FF&E and finishes (5-year), hospitality common areas like dining, commercial kitchen, salon, and activity spaces, specialty and clinical MEP such as nurse-call and emergency power, and substantial site work — typically reclassifying 21–39% of basis out of the long building schedule into 5-, 7-, and 15-year property.
Assisted living, independent living, memory care, skilled nursing, and continuing-care retirement communities (CCRCs). Each has a different mix of resident-unit FF&E, clinical infrastructure, and common-area and site work, which the study reflects on the facts of the specific facility.
Senior living facilities are operating-business properties with complex, often institutional ownership, so studies are scoped per engagement rather than self-served. Contact us with the facility details and we'll provide a proposal.
Drop your email and we'll unlock all sample reports — STR, SFR, multifamily, commercial, per-city. No spam, no nag.
One email unlocks every sample on the site. We use it to send the reports + an optional 5-day cost-seg primer (unsubscribe anytime).