Atlanta, GA · $420K
1990s build, recent reno
Year-1 federal benefit
$19,900
Conservative landlords care about CPA approval. The methodology is the same one large firms use — we just deliver it faster.
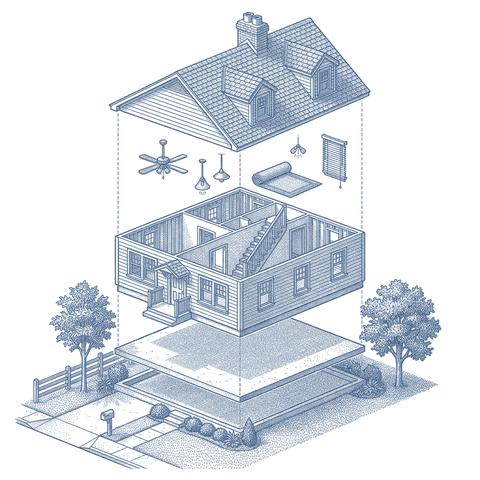
Single-family rental cost segregation is an engineering-based study that reclassifies a rental house's components out of the default 27.5-year residential schedule into faster 5- and 15-year MACRS classes. It fits landlords who own a long-term rental, because the appliances, carpet and flooring, fixtures and cabinetry (5-year) plus the driveway, landscaping, fencing, and site work (15-year) depreciate far faster than the 27.5-year building. Across delivered single-family studies the reclassified share runs 5–32% of building basis, with a typical result near 16%. Purchase price is the largest single driver: houses under $300,000 cluster in the low-to-mid teens, because a cheaper house carries less separable site work and less premium interior finish to identify, while houses above $300,000 sit closer to the middle of the range. With 100% bonus depreciation the reclassified amount is deductible in Year 1 — but the loss is passive under IRC §469, so it offsets passive income unless you qualify as a real estate professional or materially participate; confirm your situation with your CPA.
SFR cost segregation reclassifies 5–32% of depreciable basis from the 27.5- or 39-year shell into 5-, 7-, and 15-year MACRS classes per 26 U.S.C. § 168 and Rev. Proc. 87-56. Under OBBBA's permanent 100% bonus depreciation (placed-in-service 2025+), reclassified components are deductible in year one. All credible cost-seg providers use the same federal framework — industry-standard 2026 construction cost data, MACRS classification, IRS Audit Techniques Guide (Pub 5653) compliance. What differs across property types is land-allocation share, FF&E weight, and material-participation eligibility under §469.
| Property type | Reclass to 5/7/15-yr | Year-1 federal benefit | Study cost |
|---|---|---|---|
| STR | 19–39% | $45K–$280K | From $495 |
| SFR this page | 5–32% | $10K–$165K | From $495 |
| Condo | 10–17% | $18K–$68K | From $495 |
| Brownstone | 5–20% | $60K–$640K | From $495 |
| Rowhouse | 5–18% | $10K–$170K | From $495 |
| Duplex | 13–21% | $31K–$105K | From $995 |
| Fourplex | 14–29% | $56K–$230K | From $995 |
| Office | 16–29% | $84K–$650K | From $1,995 |
| Retail | 20–37% | $90K–$690K | From $1,995 |
| Industrial | 15–28% | $78K–$840K | From $2,495 |
| Self-storage | 19–36% | $140K–$1.6M | From $2,495 |
| Medical office | 16–29% | $84K–$540K | From $2,995 |
| Mixed-use | 12–23% | $63K–$515K | From $1,995 |
| Multifamily | 14–28% | $44K–$200K | From $995 |
| Multifamily 5+ | 14–26% | $110K–$1.0M | From $1,995 |
| Triplex | 14–26% | $44K–$165K | From $995 |
| Restaurant | 16–29% | $72K–$430K | From $2,995 |
| Vet | 19–36% | $85K–$540K | From $2,995 |
| Gym | 21–40% | $110K–$900K | From $2,995 |
| Dealership | 25–47% | $465K–$4.2M | From $2,995 |
| ADU | 7–14% | $8K–$39K | From $495 |
| Commercial | 18–34% | $94K–$765K | From $1,995 |
| Data center | 43–65% | $2.5M–$29M | $4,995–$54,995 (sub-$100M); $100M+ by proposal |
| Senior living | 21–39% | $315K–$2.3M | By proposal |
| Funeral homes | 18–30% | $135K–$900K | By proposal |
| Child day care | 15–28% | $56K–$630K | From $2,995 |
| Adult day care | 14–26% | $78K–$780K | From $2,995 |
| Church | 10–22% | $37K–$825K | From $2,995 |
Reclassification ranges from internal benchmarks across 4,000+ studies; Year-1 federal benefit assumes 37% bracket and full first-year usability. Study costs are Cost Seg Smart pricing — comparable engineering studies elsewhere range $5,000–$15,000+. The ADU figure is an ADU acquired with a house; one the owner built or converted is priced on its documented construction cost, from $995. See full provider comparison.
Estimates assume 37% federal bracket and full first-year usability of the loss (active income offset or REPS). Your actual benefit varies with bracket, basis allocation, and CPA's treatment.
Pre-set to SFR defaults — adjust price + bracket to match your property.
Free 1-page tool: when ordering pays, when it doesn't, plus the 3 numbers your CPA needs to file.
Yes. Any rental house you own can be studied — the appliances, flooring, fixtures, and cabinetry reclassify to 5-year property and the driveway, landscaping, and fencing to 15-year, out of the 27.5-year residential schedule. Across delivered single-family studies the reclassified share runs 5–32% of building basis, most often near 16%, and the whole reclassified amount is deductible in Year 1 under 100% bonus depreciation.
Two things, and a pool is the biggest single one. A swimming pool is a large 15-year land improvement — shell, decking, coping, filtration and equipment — and across delivered single-family studies the ones carrying a pool reclassified around 24% of depreciable basis against about 15% for the ones without. Every single-family study we have delivered above 30% had one. After that it is the ordinary content: separable site work outside (driveway, walks, fencing, landscaping, irrigation, retaining walls, exterior lighting, a deck) and identifiable interior content inside (appliances, floor coverings, window treatments, decorative lighting, cabinetry). Those are on nearly every house, so they set the middle of the range rather than the top. Purchase price is the other driver: houses under $300,000 cluster in the low-to-mid teens, because the lot is smaller and plainer, the finishes are ordinary rather than premium, and we will not claim an irrigation system or a premium kitchen we cannot evidence. That is a smaller deduction than a larger house gets, not a worse study — claiming components a property does not have is the part that fails review. If your house has work we would not assume from the price, send the documents: an inspection report, a renovation invoice, a survey or photos of the yard all move real dollars, and they move them toward your own property rather than the average one.
Yes, more than anything else we can see from the outside. A pool is depreciated as a 15-year land improvement rather than as part of the 27.5-year building, and the assembly is large: the shell, the decking and coping, the filtration, the pump and the heater. Measured across delivered single-family studies, the ones carrying a priced pool ran a median near 24% of depreciable basis and a ninetieth percentile near 30%, against a median near 15% for the ones without — a gap of about nine percentage points. A hot tub or portable spa is a smaller version of the same effect. The rest of the yard matters much less than people expect: a deck, fencing, landscaping and exterior lighting each move the result by a point or two, because almost every house has them. Declare the pool on the order form and send a photo — it is the single statement most likely to move your own number.
Usually not directly. A long-term rental loss is passive under IRC §469, so it offsets passive income unless you qualify as a real estate professional or materially participate. A short-term rental (average guest stay of 7 days or less) where you materially participate is treated differently and can offset active income. This is the single most important question to confirm with your CPA before ordering.
Single-family rentals are priced by value: from $495 for a sub-$300K property, $895 for $300K–$700K, and $995 up to $1M, delivered as a CPA-ready PDF, usually the same business day. Remote for most residential and small-commercial studies; on-site observation for larger commercial projects.
No. A lookback study lets you claim missed depreciation via Form 3115 on your current-year return under the IRS automatic-consent procedures, with no amended returns. The cumulative catch-up flows through in a single year.
Drop your email and we'll unlock all sample reports — STR, SFR, multifamily, commercial, per-city. No spam, no nag.
One email unlocks every sample on the site. We use it to send the reports + an optional 5-day cost-seg primer (unsubscribe anytime).