San Diego, CA · $640K
Beachside condo, premium finishes
Year-1 federal benefit
$30,300
Condos carry almost no 15-year land improvements (no driveway, no site work), so nearly all of the reclass is 5-year interior property.
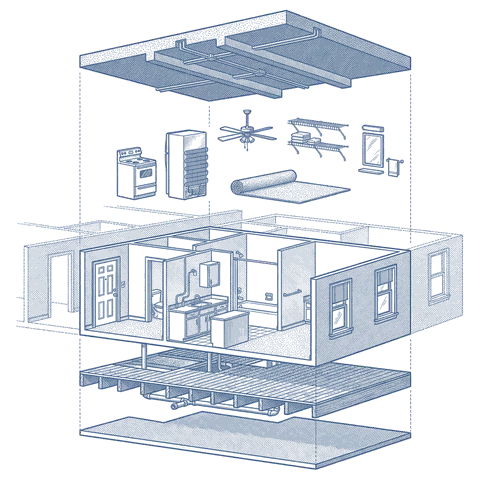
Condo and townhome cost segregation is an engineering-based study that reclassifies a rental condo's components out of the default 27.5-year residential schedule into faster 5-year MACRS classes. A condo typically reclassifies 10–19% of building basis, and the composition is distinctive: because the association typically owns the land, the exterior, and the grounds, a condo carries few 15-year land improvements of its own, so most of the reclassified amount is 5-year interior property — appliances, flooring, cabinetry, fixtures, and finishes. A condo unit owner does hold an undivided interest in the association's common elements, so the study also allocates a modest share of the unit's basis to the shared outdoor site improvements it identifies, such as parking, landscaping, and fencing, as 15-year property. Across delivered studies that puts a condo's total in line with a single-family rental rather than below it, though a short-term rental still reclassifies more. With 100% bonus depreciation that amount is deductible in Year 1, though the loss is passive under IRC §469 unless you are a real estate professional, materially participate, or the unit is a short-term rental.
Condo cost segregation reclassifies 10–19% of depreciable basis from the 27.5- or 39-year shell into 5-, 7-, and 15-year MACRS classes per 26 U.S.C. § 168 and Rev. Proc. 87-56. Under OBBBA's permanent 100% bonus depreciation (placed-in-service 2025+), reclassified components are deductible in year one. All credible cost-seg providers use the same federal framework — public government construction cost data, MACRS classification, IRS Audit Techniques Guide (Pub 5653) compliance. What differs across property types is land-allocation share, FF&E weight, and material-participation eligibility under §469. For the general explanation, see what a cost segregation study is and what the report contains.
| Property type | Reclass to 5/7/15-yr | Year-1 federal benefit | Study cost |
|---|---|---|---|
| STR | 19–39% | $45K–$280K | From $495 |
| SFR | 8–32% | $16K–$165K | From $495 |
| Condo this page | 10–19% | $18K–$76K | From $495 |
| Brownstone | 5–20% | $60K–$640K | From $495 |
| Rowhouse | 5–18% | $10K–$170K | From $495 |
| Duplex | 8–21% | $19K–$105K | From $995 |
| Fourplex | 14–29% | $56K–$230K | From $995 |
| Office | 16–29% | $84K–$650K | From $995 |
| Retail | 20–37% | $90K–$690K | From $995 |
| Industrial | 15–28% | $78K–$840K | From $2,495 |
| Self-storage | 10–36% | $75K–$1.6M | From $2,495 |
| Medical office | 16–29% | $84K–$540K | From $2,995 |
| Mixed-use | 12–23% | $63K–$515K | From $995 |
| Multifamily | 14–28% | $44K–$200K | From $995 |
| Multifamily 5+ | 14–26% | $110K–$1.0M | From $1,995 |
| Triplex | 8–26% | $25K–$165K | From $995 |
| Restaurant | 16–29% | $72K–$430K | From $2,995 |
| Vet | 19–36% | $85K–$540K | From $2,995 |
| Gym | 21–40% | $110K–$900K | From $2,995 |
| Dealership | 25–47% | $465K–$4.2M | From $2,995 |
| ADU | 7–14% | $8K–$39K | From $495 |
| Commercial | 18–34% | $94K–$765K | From $995 |
| Data center | 43–65% | $2.5M–$29M | $4,995–$54,995 (sub-$100M); $100M+ by proposal |
| Senior living | 21–39% | $315K–$2.3M | By proposal |
| Funeral homes | 18–30% | $135K–$900K | By proposal |
| Child day care | 15–28% | $56K–$630K | From $2,995 |
| Adult day care | 14–26% | $78K–$780K | From $2,995 |
| Church | 10–22% | $37K–$825K | From $2,995 |
| Farm | 8–65%† | $19K–$780K | From $995 |
Reclassification ranges from the bands we publish per property type (measured on our delivered studies where we have enough of a type, modeled elsewhere); Year-1 federal benefit assumes 37% bracket and full first-year usability. Study costs are Cost Seg Smart pricing — comparable engineering studies elsewhere range $5,000–$15,000+. The ADU figure is an ADU acquired with a house; one the owner built or converted is priced on its documented construction cost, from $995. See full provider comparison.
† Farm: the figure is property with a recovery period of 20 years or less, on a farm with one or more rental houses on it. It counts 10- and 20-year property, which no other row has, and its dollar figure is a first-year deduction, not tax saved. A farm is quoted from a list of what is on it; see how.
Illustrative, modeled properties, not client engagements. Estimates assume 37% federal bracket and full first-year usability of the loss (active income offset or REPS). Your actual benefit varies with bracket, basis allocation, and CPA's treatment.
Pre-set to Condo defaults — adjust price + bracket to match your property.
Yes — typically 10–19% of basis across delivered studies. Because the association typically owns the land and exterior, the study focuses mainly on the unit interior: appliances, flooring, cabinetry, fixtures, and finishes reclassify to 5-year property. For a condo unit it also allocates a modest share of basis to the shared outdoor site improvements you hold an interest in, as 15-year property. That interior content is why a condo's total lands close to a single-family rental's even with few land improvements of its own.
The totals are closer than most people expect — both run around 16% of depreciable basis across delivered studies — but they get there differently. A single-family rental includes the driveway, landscaping, fencing, and site work that reclassify as 15-year land improvements; a condo owner doesn't own those outright, but holds an undivided interest in the association's common elements, so the study allocates only a modest share of the unit's basis to the shared outdoor site improvements. What a condo carries instead is a higher share of 5-year interior property, so its reclass sits mostly in the 5-year class. A short-term rental still reclassifies more than either.
Condos are priced by value with single-family rentals: from $495 for a sub-$300K unit, $895 for $300K–$700K, and $995 up to $1M, delivered as a CPA-ready PDF, within 1–2 business days. Run the calculator first — the reclass is interior-only, so the benefit tracks unit value and finish level closely.
Drop your email and we'll unlock all sample reports — STR, SFR, multifamily, commercial, per-city. No spam, no nag.
One email unlocks every sample on the site. We use it to send the reports + an optional 5-day cost-seg primer (unsubscribe anytime).