Sarasota, FL · $2.4M
Purpose-built adult day health center, nurse station, bathing room, secure courtyard
Year-1 federal benefit
$432,000
An adult day center closes at night, which keeps it a commercial building — but it is fitted out like a clinic: a nurse station, a medication room, a bathing room, a serving line and a transport loading zone.
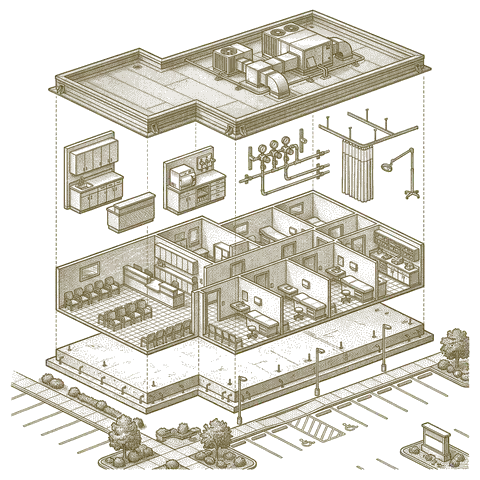
Adult day care cost segregation is an engineering-based study that reclassifies an adult day care or adult day health center's components out of the 39-year commercial building schedule into faster 5-, 7- and 15-year MACRS classes. An adult day center is a day program — participants go home at night — so it is nonresidential property on the 39-year schedule, unlike assisted living or a nursing home, where people sleep and the building is residential-occupancy. Adult day services fall in asset class 57.0, distributive trades and services, under Rev. Proc. 87-56, so qualifying personal property in the building is 5-year. What typically moves: nurse station and medication room casework, nurse-call and wander-management equipment, assisted bathing equipment and the dedicated connections serving it, therapy and activity room equipment mounts and dedicated circuits, the dining serving line and its warming and refrigeration connections, the commercial kitchen equipment, dining and activity room carpet, a salon or barber station where one is present, cameras and low-voltage cabling, and decorative lighting. Fifteen-year land improvements: the transport van loading zone and drop-off paving, accessible parking, a secure outdoor courtyard with walking path and fencing, site lighting, landscaping and signage. The shell, comfort HVAC, fire alarm, the bathing room itself and general plumbing stay 39-year. A center typically reclassifies 14–26% of basis.
Adult day care cost segregation reclassifies 14–26% of depreciable basis from the 27.5- or 39-year shell into 5-, 7-, and 15-year MACRS classes per 26 U.S.C. § 168 and Rev. Proc. 87-56. Under OBBBA's permanent 100% bonus depreciation (placed-in-service 2025+), reclassified components are deductible in year one. All credible cost-seg providers use the same federal framework — industry-standard 2026 construction cost data, MACRS classification, IRS Audit Techniques Guide (Pub 5653) compliance. What differs across property types is land-allocation share, FF&E weight, and material-participation eligibility under §469.
| Property type | Reclass to 5/7/15-yr | Year-1 federal benefit | Study cost |
|---|---|---|---|
| STR | 20–39% | $48K–$280K | From $495 |
| SFR | 8–32% | $16K–$165K | From $495 |
| Condo | 10–17% | $16K–$61K | From $495 |
| Brownstone | 5–20% | $60K–$640K | From $495 |
| Rowhouse | 5–18% | $10K–$170K | From $495 |
| Duplex | 13–21% | $31K–$105K | From $995 |
| Fourplex | 16–29% | $64K–$230K | From $995 |
| Office | 16–29% | $84K–$650K | From $1,995 |
| Retail | 20–37% | $90K–$690K | From $1,995 |
| Industrial | 15–28% | $78K–$840K | From $2,495 |
| Self-storage | 19–36% | $140K–$1.6M | From $2,495 |
| Medical office | 16–29% | $84K–$540K | From $2,995 |
| Mixed-use | 12–23% | $63K–$515K | From $1,995 |
| Multifamily | 15–28% | $48K–$200K | From $995 |
| Multifamily 5+ | 14–26% | $110K–$1.0M | From $1,995 |
| Triplex | 14–26% | $44K–$165K | From $995 |
| Restaurant | 16–29% | $72K–$430K | From $2,995 |
| Vet | 19–36% | $85K–$540K | From $2,995 |
| Gym | 21–40% | $110K–$900K | From $2,995 |
| Dealership | 25–47% | $465K–$4.2M | From $2,995 |
| ADU | 7–14% | $8K–$39K | From $495 |
| Commercial | 18–34% | $94K–$765K | From $1,995 |
| Data center | 43–65% | $2.5M–$29M | $4,995–$54,995 (sub-$100M); $100M+ by proposal |
| Senior living | 21–39% | $315K–$2.3M | By proposal |
| Funeral homes | 18–30% | $135K–$900K | By proposal |
| Child day care | 15–28% | $56K–$630K | From $2,995 |
| Adult day care this page | 14–26% | $78K–$780K | From $2,995 |
| Church | 10–22% | $37K–$825K | From $2,995 |
Reclassification ranges from internal benchmarks across 4,000+ studies; Year-1 federal benefit assumes 37% bracket and full first-year usability. Study costs are Cost Seg Smart pricing — comparable engineering studies elsewhere range $5,000–$15,000+. See full provider comparison.
Estimates assume 37% federal bracket and full first-year usability of the loss (active income offset or REPS). Your actual benefit varies with bracket, basis allocation, and CPA's treatment.
Pre-set to Adult day care defaults — adjust price + bracket to match your property.
No, and the distinction is the whole point. An adult day center closes at night: nobody sleeps there, so it is nonresidential real property on the 39-year schedule. Assisted living, memory care and skilled nursing are residential-occupancy facilities and depreciate differently. It matters for the study too, because the fit-out is different — a day center has no resident rooms, which is where a senior living facility carries most of its furniture and finishes.
Typically to 5-year: nurse station and medication room casework, including locked med storage and the charting counter; nurse-call, monitoring and wander-management equipment; assisted bathing or spa tub equipment and the dedicated supply and tempering serving it; therapy and activity room equipment mounts, mirrors and dedicated circuits; the dining serving line casework and its warming and refrigeration connections; commercial kitchen equipment and its dedicated plumbing, gas and hood exhaust; dining and activity room carpet and removable resilient flooring; a salon or barber station where one is present; cameras and low-voltage cabling; decorative and accent lighting. To 15-year: the transport van loading zone and drop-off paving, bollards and striping, accessible parking, a secure outdoor courtyard with its walking path, garden beds and wander-secure fencing, site lighting, landscaping, sidewalks and the monument sign.
The shell and roof, interior partitions, comfort HVAC, sprinklers and the fire alarm, which is life safety and part of the building, the bathing room itself along with its floor drain and general plumbing, restrooms, and general lighting. The drop-off canopy structure is building too, even though the paving under it is a 15-year land improvement — a useful illustration of how the line gets drawn.
The building owner's. The landlord depreciates the building, the site work and whatever conveyed with the purchase. The operator depreciates its own equipment and any build-out the operator paid for, which is a leasehold improvement study on the operator's return. If you own both, you get both, and the intake asks what was included in the purchase so nothing is counted twice.
It usually helps, because a medical office already has the plumbing and electrical capacity a day health program needs, and because the conversion cost is generally documented. Documented costs are used in place of modeled ones wherever you have them, which makes the result both sharper and easier to support. A converted residence is the weaker form — small lot, no bathing room, no salon — and it sits at the floor of the band.
The address, the purchase price and closing date, square footage, year built, whether there is a nurse station, bathing room or salon, and whether equipment or furnishings were included in the purchase. A closing statement, a lease if the building is leased to an operator, and any build-out invoices sharpen the result. If the building was placed in service in a prior year, a Form 3115 lookback captures the missed depreciation in the current year.
Drop your email and we'll unlock all sample reports — STR, SFR, multifamily, commercial, per-city. No spam, no nag.
One email unlocks every sample on the site. We use it to send the reports + an optional 5-day cost-seg primer (unsubscribe anytime).