Family-owned funeral home, converted residence · By proposal
Chapel AV and lighting, selection room millwork, visitation finishes, service parking
Year-1 federal benefit
Custom-scoped
A funeral home is three buildings in one: a licensed preparation room, a chapel, and a parking lot sized for a procession. Each carries property that does not belong on the 39-year schedule.
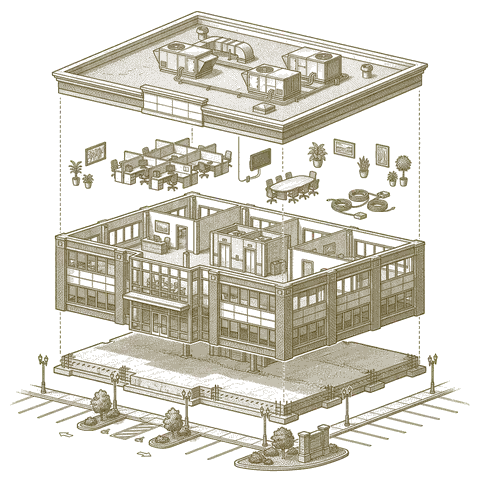
Funeral home cost segregation is an engineering-based study that reclassifies a funeral home's components out of the 39-year building schedule into faster 5-, 7-, and 15-year MACRS classes. Funeral service is asset class 57.0, distributive trades and services, under Rev. Proc. 87-56, so qualifying personal property in the facility is 5-year. What typically moves is identified room by room: the preparation and embalming room (dedicated plumbing, floor drains, the ventilation and exhaust serving the process, stainless fixtures, walk-in refrigeration), the chapel (audio-visual and sound systems, decorative and accent lighting, millwork, carpet), the casket and urn selection room (display lighting, millwork, casework), visitation lounges and family rooms (furniture, kitchenette equipment, finishes), offices (furniture, data cabling), and the crematory retort with its dedicated exhaust where one is present. Site work is unusually large for the building size, because the lot is sized for a procession rather than for the building: service parking, drive lanes, site lighting, landscaping and signage are 15-year land improvements. The shell, roof, general HVAC, general electrical and general plumbing stay 39-year. An estimated 18–30% of basis reclassifies, and studies are scoped per engagement rather than self-served, so contact us for a proposal.
Funeral homes cost segregation reclassifies 18–30% of depreciable basis from the 27.5- or 39-year shell into 5-, 7-, and 15-year MACRS classes per 26 U.S.C. § 168 and Rev. Proc. 87-56. Under OBBBA's permanent 100% bonus depreciation (placed-in-service 2025+), reclassified components are deductible in year one. All credible cost-seg providers use the same federal framework — industry-standard 2026 construction cost data, MACRS classification, IRS Audit Techniques Guide (Pub 5653) compliance. What differs across property types is land-allocation share, FF&E weight, and material-participation eligibility under §469.
| Property type | Reclass to 5/7/15-yr | Year-1 federal benefit | Study cost |
|---|---|---|---|
| STR | 20–39% | $48K–$280K | From $495 |
| SFR | 8–32% | $16K–$165K | From $495 |
| Condo | 10–17% | $16K–$61K | From $495 |
| Brownstone | 5–20% | $60K–$640K | From $495 |
| Rowhouse | 5–18% | $10K–$170K | From $495 |
| Duplex | 13–21% | $31K–$105K | From $995 |
| Fourplex | 16–29% | $64K–$230K | From $995 |
| Office | 16–29% | $84K–$650K | From $1,995 |
| Retail | 20–37% | $90K–$690K | From $1,995 |
| Industrial | 15–28% | $78K–$840K | From $2,495 |
| Self-storage | 19–36% | $140K–$1.6M | From $2,495 |
| Medical office | 16–29% | $84K–$540K | From $2,995 |
| Mixed-use | 12–23% | $63K–$515K | From $1,995 |
| Multifamily | 15–28% | $48K–$200K | From $995 |
| Multifamily 5+ | 14–26% | $110K–$1.0M | From $1,995 |
| Triplex | 14–26% | $44K–$165K | From $995 |
| Restaurant | 16–29% | $72K–$430K | From $2,995 |
| Vet | 19–36% | $85K–$540K | From $2,995 |
| Gym | 21–40% | $110K–$900K | From $2,995 |
| Dealership | 25–47% | $465K–$4.2M | From $2,995 |
| ADU | 7–14% | $8K–$39K | From $495 |
| Commercial | 18–34% | $94K–$765K | From $1,995 |
| Data center | 43–65% | $2.5M–$29M | $4,995–$54,995 (sub-$100M); $100M+ by proposal |
| Senior living | 21–39% | $315K–$2.3M | By proposal |
| Funeral homes this page | 18–30% | $135K–$900K | By proposal |
| Child day care | 15–28% | $56K–$630K | From $2,995 |
| Adult day care | 14–26% | $78K–$780K | From $2,995 |
| Church | 10–22% | $37K–$825K | From $2,995 |
Reclassification ranges from internal benchmarks across 4,000+ studies; Year-1 federal benefit assumes 37% bracket and full first-year usability. Study costs are Cost Seg Smart pricing — comparable engineering studies elsewhere range $5,000–$15,000+. See full provider comparison.
Estimates assume 37% federal bracket and full first-year usability of the loss (active income offset or REPS). Your actual benefit varies with bracket, basis allocation, and CPA's treatment.
Pre-set to Funeral homes defaults — adjust price + bracket to match your property.
Yes. Funeral service is asset class 57.0, distributive trades and services, under Rev. Proc. 87-56, so qualifying personal property in the facility is 5-year. A study separates the preparation room's dedicated plumbing, drains, ventilation and refrigeration, the chapel's audio-visual and lighting systems, selection room millwork and display lighting, and visitation and office furnishings from the 39-year shell, and treats the service parking, drive lanes, site lighting and landscaping as 15-year land improvements. An estimated 18–30% of basis reclassifies, on the facts of the specific facility.
Reclassified, typically: the preparation and embalming room (dedicated plumbing, floor drains, the ventilation and exhaust serving the process, stainless fixtures, walk-in refrigeration), the chapel (audio-visual and sound, decorative and accent lighting, millwork, carpet), the casket and urn selection room (display lighting, millwork, casework), visitation lounges and family rooms (furniture, kitchenette equipment, finishes), offices (furniture, data cabling), and a crematory retort with its dedicated exhaust where present. Stays 39-year: the shell, the roof, and the general HVAC, electrical and plumbing serving the building as a whole. Many funeral homes are converted large residences or purpose-built single-story chapels, and in both cases that shell is the long-lived part.
Because the lot is sized for a procession rather than for the building. Large service parking areas, drive lanes for vehicles forming up, site lighting, landscaping and signage are 15-year land improvements, and on a funeral home they are unusually large relative to the building footprint. That is the single most common reason a funeral home reclassifies more than an office of the same size.
By proposal, scoped per engagement. The facilities vary widely, from a converted residence with a chapel added to a purpose-built facility with a crematory, and a consolidator acquiring several locations at once is a different scope again. Send us the property details and we will put a proposal together.
Drop your email and we'll unlock all sample reports — STR, SFR, multifamily, commercial, per-city. No spam, no nag.
One email unlocks every sample on the site. We use it to send the reports + an optional 5-day cost-seg primer (unsubscribe anytime).