Land Improvements Depreciation Life: 15 Years, and What Actually Qualifies
Fifteen years, 150% declining balance, bonus-eligible. What counts as a land improvement, what stays 39-year building, and what is non-depreciable land — with line-by-line numbers from two studies that shipped this week.
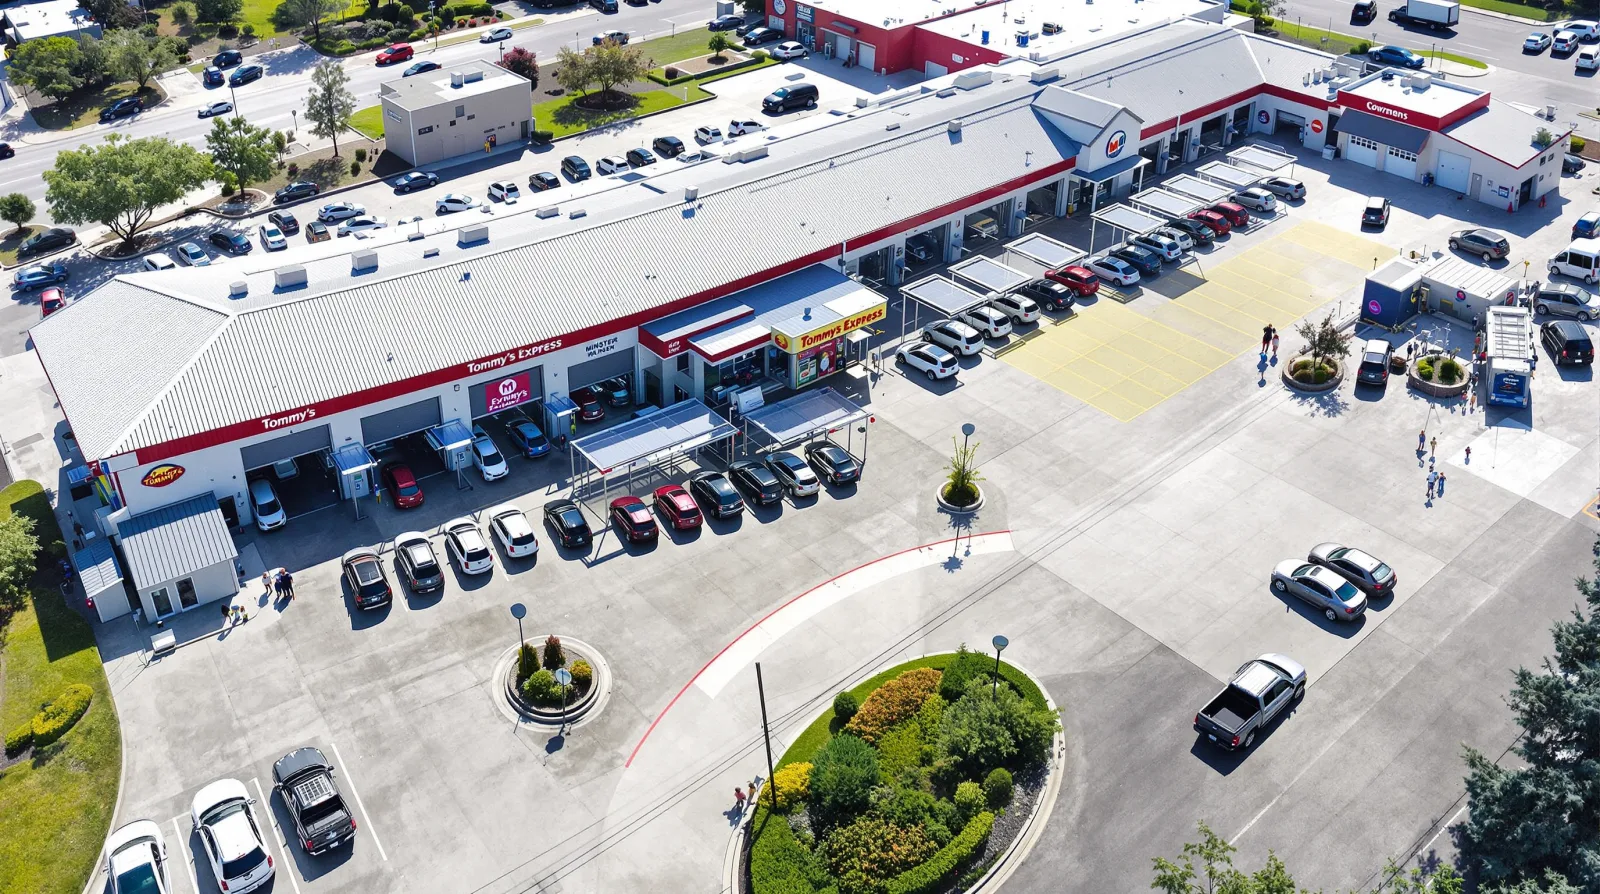
Land improvements depreciate over 15 years under MACRS, using the 150% declining balance method and a half-year convention. They are Rev. Proc. 87-56 asset class 00.3 — parking lots, sidewalks, site lighting, fencing, drainage structures and building-adjacent landscaping — and they are eligible for 100% bonus depreciation, so most owners deduct them entirely in year one.
Land improvements depreciate over 15 years under MACRS, at 150% declining balance with a half-year convention, and because 15 years is under the 20-year ceiling they are eligible for 100% bonus depreciation. They live in asset class 00.3 of Rev. Proc. 87-56, the class the IRS simply labels “land improvements,” and they cover nearly everything on the site that is neither the building nor raw dirt: paving, sidewalks, site lighting, fencing, retaining walls, drainage structures, signage foundations, and the landscaping planted against the building.
That is the answer. The rest of this post is what decides whether you actually collect it — the 15-year class is the most reliably overlooked money in a commercial purchase, and on some property types the site is worth more than anything inside the walls.
| What you bought | Recovery period | Authority | Bonus-eligible |
|---|---|---|---|
| Land: dirt, grading, general excavation | Never depreciated | Not a wasting asset | No |
| Land improvements: the site work | 15 years, 150% DB | Rev. Proc. 87-56, class 00.3 | Yes |
| Tangible personal property | 5 or 7 years | Classes 00.11, 00.12 | Yes |
| The building shell | 39 years commercial, 27.5 residential | IRC §168(c) | No |
Three of those four rows arrive on the same closing statement, undifferentiated, under one word: improvements. A cost segregation study takes that word apart. Our components list inventories 43 of them with the authority for each, the MACRS guide covers the recovery tables, and the calculator will price your own building first.
Why does 15-year property get missed so consistently?
Because on a purchase there is no invoice for it. You get a price, a land-versus-improvements allocation, and a building. Nothing in that chain separates the parking lot from the roof. Your CPA gets one number for improvements and puts it on the 39-year line — the default the code hands them — and the site work rides along for four decades at roughly two and a half cents on the dollar per year.
The IRS Cost Segregation Audit Techniques Guide treats this as an engineering question rather than an accounting one. Somebody has to measure the site, which is why our study process reads the site plan and aerial imagery as primary evidence.
The second reason is psychological. Site work looks like landscaping, and landscaping sounds like a small number. It isn’t — on the two studies below, the 15-year class alone runs $111,059 and $152,497.
What qualifies as a land improvement, and what does not?
The dividing line runs two directions at once — the building above, on 39 years, and the land below, on no schedule at all. Land improvements are the middle band, and both edges leak.
The qualifies and does-not-qualify table
| Qualifies: 15-year, class 00.3 | Does not: what it is instead |
| Asphalt and concrete paving, base course, striping | General site grading and excavation — land |
| Curbs, gutters, wheel stops, bollards | Fill placed to establish the building pad — land |
| Sidewalks, plazas, exterior stairs and ramps | The building’s entry vestibule — 39-year building |
| Pole-mounted and bollard site lighting | Lighting mounted on the building and serving it — 39-year |
| Fencing, gates, self-closing hardware | An interior partition wall — 39-year |
| Retaining walls and site walls | A foundation wall carrying building load — 39-year |
| Storm drainage structures, inlets, piping, liners | The basin excavation itself — land |
| Irrigation, and landscaping adjacent to the building | Perimeter trees and general lawn — land |
| Exterior monument signage and its foundation | Signage attached to the building facade — 39-year |
| Flagpoles, freestanding shade structures, car canopies | A canopy structurally tied into the building — 39-year |
Notice how many rows in the right column are the same object in a different position. That is where studies go wrong.
Why “it is removable” is one factor out of six
The argument people reach for first is that a component can be taken out without damaging the building. That is a real test — but it is one prong of a six-part analysis, and citing it alone is a weak position.
The six factors come from Whiteco Industries, Inc. v. Commissioner, 65 T.C. 664 (1975). They ask whether the property can be moved and has in fact been moved; whether it was designed to remain permanently in place; whether circumstances suggest it may have to be moved; how substantial and time-consuming removal is; how much damage removal causes; and what the manner of affixation is. An argument built on removability alone has answered one of six and ignored five.
For land improvements the Whiteco factors usually cut toward permanence, which is exactly the point. A parking lot is permanent and it is still 15-year property, because class 00.3 is a class-life question rather than a §1245 personal-property question. Your site work doesn’t have to be personal property — it has to be correctly identified as site work.
What is the depreciation life of a parking lot?
Fifteen years — and the lot is usually the single largest 15-year line on any commercial property with surface parking. What belongs to it: the wearing course, the aggregate base beneath it, seal coat, striping, wheel stops, bollards, curb and gutter, catch basins within the lot, and the pole lighting that serves it. What does not: the cut and fill that made the ground flat enough to pave.
Parking lot depreciation, year by year
Under the IRS 15-year table, a $51,304 parking allocation recovers like this. The right-hand column is what bonus depreciation does to the same number.
| Year | 15-year table rate | Deduction without bonus | With 100% bonus |
|---|---|---|---|
| 1 | 5.00% | $2,565 | $51,304 |
| 2 | 9.50% | $4,874 | $0 |
| 3 | 8.55% | $4,387 | $0 |
| 4 | 7.70% | $3,950 | $0 |
| 5–15 | remainder | $35,528 total | $0 |
Same total deduction either way — the difference is entirely timing, and timing at a 37% marginal rate is worth roughly $18,000 of present-value deferral on this one line. Our calculator runs your own basis through the same logic in about a minute.
What does 15-year property look like on a child day care?
A child day care center is a small building sitting in the middle of a very expensive yard, which makes the point cleanly.
The property: 9,500 square feet, $1,600,000 purchase price, $1,392,000 of depreciable basis after the land carve-out. The 15-year class came to $152,497, which is 11.0% of basis and about $16.05 for every square foot of building.
| 15-year line | Why it is site work |
|---|---|
| Poured-in-place playground safety surfacing | A site surface with its own containment curbs and subsurface drainage |
| Anchored play structures and shade sails | Affixed site equipment, held at 15-year by policy (see below) |
| Perimeter fencing with self-closing gates | Class 00.3 fencing; the licensing requirement does not change the class |
| Staged parent drop-off lane | Paving, curb and striping, priced separately from the general lot |
| Site lighting, walks, landscaping, irrigation | The ordinary 00.3 package every site carries |
The safety surfacing is the line most studies drop, because it reads as a playground expense rather than a construction system. It’s poured in place over a prepared base, it has containment curbs, and it drains to a subsurface system. Line-by-line detail sits in the child day care sample report, and the percentages post sets expectations by type.
Why does a house of worship put more money in the parking lot than in the sanctuary?
Because a sanctuary lot is sized for the seat count, not the floor area. Parking ordinances tie stall counts to seats, and a room full of chairs holds far more people per square foot than an office floor does — so a modest building can carry a lot sized for a small shopping center.
The property: 14,000 square feet, $2,200,000 purchase price, $1,848,000 of depreciable basis. The 15-year class came to $111,059, or 6.0% of basis — about $7.93 per square foot of building.
| 15-year line | Amount | Share of 15-year |
|---|---|---|
| Parking lot paving and striping | $51,304 | 46.2% |
| Sidewalks, plazas and exterior paving | $17,143 | 15.4% |
| Site lighting | $12,082 | 10.9% |
| Landscaping and irrigation | $10,423 | 9.4% |
| Exterior monument signage | $7,043 | 6.3% |
| Stormwater detention | $6,649 | 6.0% |
| Perimeter fencing | $6,415 | 5.8% |
| Total 15-year property | $111,059 | 100% |
The two studies make the same argument from opposite directions — a small building with a big play area, and a big room with a bigger lot. In both, the money is outside the walls, and nothing on the closing statement said so. The house of worship hub explains the classification, and the sample report carries the full schedule, including why its personal property lands in the 7-year class rather than the 5-year one.
| 15-year property | Share of basis | Largest single line | |
|---|---|---|---|
| Child day care, 9,500 SF | $152,497 | 11.0% | Playground surfacing system |
| House of worship, 14,000 SF | $111,059 | 6.0% | Parking, $51,304 |
Where does the 15-year boundary actually get lost?
In three specific places. Each is a real classification we’ve argued through, and each costs money in a different direction.
Stormwater detention: the structure is depreciable, the hole is not
A detention basin has two halves on two different schedules. The concrete or engineered structure, the liner, the inlet grates, the control weir and the outfall piping are 15-year land improvements. The excavation that formed the basin is part of the land and is never depreciated, because holding water does not consume the land.
The same rule governs general site excavation and rough grading. Moving dirt to make a site buildable improves the land permanently, and permanently isn’t a recovery period. A practitioner who sweeps the whole site-work invoice into 15-year property has depreciated the dirt — the kind of error an examiner finds by reading one line of a schedule of values.
The van loading zone and the canopy above it
On an adult day care center the transport van is central to the operation, so the site carries a dedicated loading zone: paving, bollards, striping, and a marked accessible path. All of it is 15-year land improvement property.
The drop-off canopy over it is 39-year building. It is structurally tied to the building, it shelters an entrance, and it is an inherently permanent part of the structure under §1250. Same twenty feet of ground, two schedules — the split runs vertically rather than horizontally. A freestanding car canopy out in the lot, with no connection to the building, goes back to 15-year.
Landscaping counts only when it is next to the building
The adjacency test is narrower than most people expect. Landscaping is depreciable when it sits adjacent to the building and would be destroyed if the building were replaced. Shrub beds against the foundation, the irrigation heads serving them, the trees in a parking island — those qualify. The mature oaks along the back line do not, and neither does the general lawn, because replacing the building would never touch them.
| The same item, in two places | Classification |
|---|---|
| Shrub bed against the foundation wall | 15-year land improvement |
| Identical shrub bed at the rear property line | Land, not depreciated |
| Irrigation zone serving the foundation planting | 15-year land improvement |
| Grading and topsoil across the undeveloped acre | Land, not depreciated |
What happens when the boundary moves the other way?
This is the part most explainers leave out, so here is ours with the defect named.
Our line classifier once pulled anchored playground climbers out of 15-year and into 5-year. The reason was mechanical rather than analytical — the component name contains the word “equipment,” and the rule order sorts equipment ahead of site work. Nothing about the property changed. A string match did.
That is over-acceleration, the direction a classifier exists to prevent. A 5-year climber produces a bigger year-one number than a 15-year one, so the error flatters the study and costs the client later, at review or on sale. A guard now holds playground structures at 15-year, and our QC checks classifier output against the schedule rather than trusting the rule that produced it.
The honest nuance is why that guard is overridable rather than absolute. A climber bolted into poured-in-place surfacing is a land improvement, straightforwardly. A free-standing swing set on grass, delivered on a truck and movable by four people, is arguably personal property under the Whiteco factors. A component name can’t tell those apart — a photograph and an installation detail can. If a study reclassified something in your favor and nobody can say which of the six factors carried it, that’s worth asking about, and it’s the same question we ask of our own output.
When is 15-year property not worth chasing?
When there is no site. That disqualifier is real.
An inline retail bay has an entry door, a demising wall on each side, and no exclusive site area. The parking sits in the landlord’s basis, not yours. A commercial condominium unit is the same story — the common site work belongs to the association, and your deed conveys air and finishes. There the 15-year class is a rounding error, and a study should be scoped and priced for the building alone; the tenant improvement path is usually the right one.
Two more cases where the site math does not carry a study:
- Structured parking. A parking deck integral to the building is generally 39-year structure, not a land improvement.
- A ground lease. The site work may be yours, but the analysis turns on lease terms and what reverts to the landowner, not on class 00.3.
Our pricing is published by type and basis, so you can tell before ordering whether the numbers justify it.
You already own the property — is the 15-year money gone?
No, and you do not amend a single return
You do not amend prior returns to catch missed depreciation. Your CPA files a Form 3115 change in accounting method and takes the whole cumulative catch-up as a §481(a) adjustment in the current year, under the IRS automatic-consent procedures. On a building bought years ago with a large site, that catch-up is frequently the biggest single deduction on the return.
The mechanics are in the Form 3115 and §481(a) guide and the lookback study post. One thing changes the answer: a sale. If the property is gone, so is the opportunity, which is why selling soon is the question to settle first. The calculator shows the catch-up before you commit to anything.
What to hand your CPA
A schedule that names every 15-year line, prices it, and cites its class — not a percentage. An engineering-based study built from industry-standard construction cost data, with internal technical review and QC on every component, produces exactly that, and the site work is the section your CPA is least likely to reconstruct without help.
If you have a paving invoice, a site-work schedule of values, or civil drawings from a build-out, send them. A documented line beats a modeled line, and site work is where documentation most often exists and most often goes unmentioned. Here is what to gather; you can start an order or browse the samples first.
This article is general information about depreciation rules, not tax advice. Recovery periods, bonus depreciation and recapture all turn on facts specific to your property and your return. Talk to your CPA or tax adviser before acting on any of it.
Free preliminary depreciation estimate — property summary, basis allocation, five-year schedule. We do the work; you get the PDF.
See my estimated Year-1 savings →Frequently asked
How long do you depreciate land improvements?
Land improvements are 15-year property under the MACRS General Depreciation System, recovered with the 150% declining balance method and a half-year convention. They belong to asset class 00.3 of Rev. Proc. 87-56. Under the Alternative Depreciation System the life is 20 years instead. Because a 15-year recovery period is under the 20-year ceiling, land improvements qualify for bonus depreciation, so most owners deduct the full amount in the year the property is placed in service rather than spreading it across fifteen.
What is the depreciation life of a parking lot?
A parking lot is 15-year land improvement property. That covers the asphalt or concrete surface, the aggregate base beneath it, striping, curbs, wheel stops, bollards, and the pole lighting that serves the lot. The grading and excavation that prepared the site are not depreciable at all; they stay in the basis of the land. On the house of worship study described below, the parking line alone came to $51,304 on a 14,000 square foot building, roughly 46 percent of every 15-year dollar in that study.
Are land improvements eligible for bonus depreciation?
Yes. Bonus depreciation under IRC §168(k) applies to property with a recovery period of 20 years or less, and 15-year land improvements clear that test. The One Big Beautiful Bill Act made 100 percent bonus permanent for property placed in service on or after January 20, 2025. So a $152,497 allocation to 15-year property is a $152,497 deduction in year one instead of the $7,624 the ordinary 15-year table would give you. The reclassification creates the deduction; bonus is what pulls it forward.
Is excavation a land improvement or is it land?
It depends on what the excavation was for. General site excavation and grading are inseparable from the land and are not depreciable, because land does not wear out. Excavation so closely associated with a depreciable improvement that it would be retired along with it can follow that improvement. The common trap is a stormwater detention basin: the concrete structure, the liner, the inlet and the outfall piping are 15-year property, while the hole itself stays with the land.
Is landscaping depreciable?
Landscaping is depreciable as a 15-year land improvement only when it sits adjacent to the building and would be destroyed if the building were replaced. Shrub beds against the foundation, the irrigation zone that waters them, and trees planted in a parking island generally qualify. A row of mature trees at the back of the parcel, general lawn, and site grading are part of the land and are never depreciated. The IRS Cost Segregation Audit Techniques Guide walks through that proximity test.
What is the difference between a land improvement and qualified improvement property?
Both are 15-year property and both are bonus-eligible, but they are different classes with different rules. A land improvement is site work outside the building, classified under Rev. Proc. 87-56 asset class 00.3. Qualified improvement property is an interior improvement to an existing nonresidential building, placed in service after the building was first placed in service by anyone. Enlargements, elevators, escalators and internal structural framework are carved out of QIP by statute. Land improvements carry no such exclusion list.
What happens to land improvements when you sell the property?
Land improvements are generally section 1250 property, depreciable real property rather than personal property, but the 15-year class recovers them with an accelerated method. Depreciation claimed above straight line, including bonus depreciation, is additional depreciation that can come back as ordinary income under §1250 on sale. The remaining depreciation-related gain is unrecaptured section 1250 gain, taxed at up to 25 percent. Run that math with your CPA before you order, especially if you expect to sell within a few years.
Do I need a site visit to value the land improvements?
Usually not. Site work is the one part of a property that is visible from above, so aerial imagery, the plat, the site plan and the civil drawings carry most of the measurement: square feet of paving, linear feet of curb and fence, the count of light poles, the footprint of the detention basin. What matters more than a visit is documentation. A paving invoice or a site-work schedule of values moves a line from modeled to documented, and documented lines survive review far better.