Cost Segregation on a Duplex: About the Same Share as a Single-Family Rental
A duplex typically reclassifies 8–21% of depreciable basis, most often around 15%. On a $400K duplex that's roughly $48,000 of Year-1 deductions after a 20% land carve-out. Same 27.5-year residential schedule as a single-family — two kitchens, two bathrooms and two sets of appliances are what the study itemizes.
A duplex typically reclassifies 8–21% of depreciable basis, most often around 15%. On a $400K duplex that's roughly $48,000 of Year-1 deductions after a 20% land carve-out. Same 27.5-year residential schedule as a single-family — two kitchens, two bathrooms and two sets of appliances are what the study itemizes.
A duplex typically reclassifies 8–21% of depreciable basis through cost segregation, most often around 15%. On a $400K duplex with a typical 20% land allocation, that’s roughly $48,000 of basis accelerated from the default 27.5-year residential MACRS schedule into 5-, 7-, and 15-year property classes, fully deductible in Year 1 under 100% bonus depreciation restored by the OBBBA. Federal tax savings at a 37% bracket: roughly $17,760. State savings add 3–13% on top depending on whether your state conforms to §168(k).
This guide is for the investor who owns both units of a duplex as a long-term rental. If you live in one half and rent the other (house-hacking), the §469 passive-loss rules and §121 exclusion change the math materially — we have a dedicated guide for that. Everything below assumes pure-investor duplex ownership.
What makes duplex cost seg different from SFR
The per-unit FF&E multiplier. Every dwelling unit in a building carries its own kitchen, bathroom, flooring, and often its own HVAC system. These are all categorized as 5-year personal property under MACRS (Rev. Proc. 87-56) — cabinetry, appliances, plumbing fixtures, light fixtures, carpet, and finish work. A single-family rental has one of each. A duplex has two.
The bands we publish per property type show how the small-residential types compare:
| Property type | Most often around | Typical range |
|---|---|---|
| Single-family rental | 15% | 8–32% |
| Duplex | 15% | 8–21% |
| Triplex | 17% | 8–26% |
| Fourplex | 19% | 14–29% |
| Multifamily 5+ | 17% | 14–26% |
The ranges overlap heavily. A second unit doubles the kitchens, bathrooms and appliances, but the shell and site grow with it, so the percentage does not climb unit by unit — the dollars do. Buildings of five or more units lean on shared systems (one common HVAC plant, one shared elevator), which is part of why their range tops out lower.
Real numbers: $400K duplex Year-1 breakdown
An illustrative example at the representative rate, with 20% land allocation and 100% bonus depreciation:
| Line item | Amount |
|---|---|
| Purchase price | $400,000 |
| Land allocation (excluded) | $80,000 (20%) |
| Depreciable basis | $320,000 |
| Reclassified to 5/7/15-year (15%, representative) | $48,000 |
| Year-1 deduction (100% bonus) | $48,000 |
| Federal tax savings at 37% bracket | $17,760 |
| Federal tax savings at 32% bracket | $15,360 |
| Federal tax savings at 24% bracket | $11,520 |
| Cost Seg Smart study cost (duplex, $300K–$700K) | $1,295 |
| Net Year-1 federal benefit at 37% | $16,465 |
| ROI | 14× |
At a 37% federal bracket plus a 9% state in a conforming state, total Year-1 tax savings come to roughly $22,080 on a $1,295 study. The standard 27.5-year schedule on the same property delivers ~$11,600/year — meaning cost segregation moves roughly 4 years of “default depreciation” into Year 1.
For larger duplexes ($600K–$900K), federal Year-1 savings at the representative rate come to roughly $26,640–$39,960 at the 37% bracket. Anything over $1M depreciable basis routes to our $500K–$1M cost segregation guide.
The components that drive duplex reclassification
A typical duplex study reclassifies basis into three MACRS class lives:
5-year personal property (usually the largest share):
- Cabinetry and countertops (both kitchens, both bathrooms)
- Appliances — refrigerator, range, dishwasher, microwave (per unit)
- Carpet and resilient flooring (vinyl, LVT)
- Light fixtures, ceiling fans
- Window treatments built into the assignment
- Specialty plumbing fixtures (e.g., tub surrounds, sinks beyond rough-in)
7-year personal property (usually small):
- Office furniture if any unit serves as a home-office STR
- Decorative MEP elements not affixed to structure
15-year land improvements:
- Driveway and parking pad
- Site lighting and exterior fixtures
- Fencing and gates
- Landscaping (graded site work, retaining walls, hardscape)
- Exterior signage and unit numbering hardware
- Utility connections from the meter to the building
The rest — most of the basis — stays on the 27.5-year residential schedule — building shell, roof structure, plumbing rough-in, electrical service, foundation, and HVAC distribution (though the HVAC condenser/air-handler unit itself often qualifies for the 5- or 15-year carve depending on configuration).
Engineering-based studies attribute every dollar of basis to a specific MACRS class with documented cost-source backing (industry-standard construction cost data in our case). Rule-of-thumb studies that simply apply “20% reclass” without component documentation are the type Pub 5653 explicitly warns examiners about. See our audit-defense scope for the 13 quality elements every Cost Seg Smart deliverable addresses.
Duplex stays 27.5-year residential — even 2 units
One of the most common misconceptions among new investors: more than one unit means commercial. Wrong.
Under IRC §168(e)(2)(A) and IRS Pub. 946, a building qualifies as residential rental property (27.5-year MACRS recovery period) when 80% or more of gross rental income comes from “dwelling units.” A unit is a dwelling unit if it has cooking, sleeping, and bathing facilities — i.e., a residence.
A duplex with two long-term residential tenants generates 100% of its rents from dwelling units. It’s residential. Same depreciation schedule as a single-family rental. The unit count test only kicks in when at least 20% of rent comes from non-dwelling commercial use (a duplex with a ground-floor storefront, for example).
This matters because investors sometimes assume their duplex must be classified as 39-year commercial after talking to a tax preparer who’s only handled SFRs. Mis-classifying as 39-year leaves about 30% of accelerated depreciation on the table. If your prior tax returns used the 39-year schedule on a residential duplex, Form 3115 lets you correct the error and recapture the difference as a §481(a) adjustment.
When duplex cost segregation makes sense — and when it doesn’t
Strong fit:
- Duplex purchase price ≥ $300K
- Holding the property at least 5 years (depreciation recapture math improves with longer holds)
- You have current-year tax liability to offset — W-2 wages with REPS, rental portfolio with offsetting passive income, or business income
- Property placed in service 2025 or later (100% bonus depreciation post-OBBBA)
- Material participation criteria met if you want to offset W-2 income — for STR duplexes see our STR material participation guide
Marginal fit:
- Duplex $200K–$300K — study fee starts eating into Year-1 benefit. Run the cost segregation calculator before ordering.
- Plan to sell within 2–3 years — recapture exposure may offset the timing benefit unless you 1031 exchange
- Passive investor with no offsetting passive income — accelerated deductions get suspended under §469 and only release on disposition
Poor fit:
- Duplex under $200K — fixed study cost dominates the benefit math
- Bought in a tax year with little or no federal income tax liability
- Property used personally — duplex with one owner-occupied unit is a house-hacking scenario with different rules
If you’re not sure where your duplex lands, the decision worksheet above runs the numbers in two minutes.
What a duplex study costs and what you actually get
Cost Seg Smart pricing for duplex studies is flat by basis tier: $995 under $300K, $1,295 for $300K–$700K and $1,495 for $700K–$1M. That covers:
- 40+ page engineered report with component-level depreciation schedules
- MACRS class assignments per Rev. Proc. 87-56 (5, 7, 15, 27.5)
- Land allocation using county assessor data + statistical fallback
- Year-by-year depreciation tables formatted for Form 4562
- Methodology section citing IRS Pub. 5653 and the 13 quality elements
- Quality-checked before delivery
- Form 3115 §481(a) readiness if this is a lookback study (any duplex placed in service before this tax year)
- CPA-Ready Guarantee — free corrections if your CPA flags a format problem on our side
- Audit-support scope per /audit-defense/ — full workpaper documentation in the report, plus written answers to your CPA’s methodology questions at no charge for the life of the study
Traditional engineering firms typically quote $3,500–$8,000 for a duplex study with 4–8 week turnaround and an on-site visit. The methodology under Pub 5653 is identical — what you’re paying for is labor model, not engineering. For a deeper price-tier comparison see How much does a cost segregation study cost and the Cost Segregation Reviews provider comparison.
How it compares to other small multi-family
If you’re evaluating a duplex vs a triplex or fourplex acquisition, cost segregation isn’t a tie-breaker but it does shift the math. (For the three-unit case in detail, including which of the three furnaces, water heaters and kitchens actually reclassify, see our triplex cost segregation guide.)
| Property | Most often around | Year-1 fed savings* | Study cost |
|---|---|---|---|
| SFR ($400K) | 15% | $17,760 | $895 |
| Duplex ($400K) | 15% | $17,760 | $1,295 |
| Triplex ($600K) | 17% | $30,192 | $1,295 |
| Fourplex ($800K) | 19% | $44,992 | $1,495 |
| Multifamily 5+ ($1.4M) | 17% | $70,448 | $3,595 |
*Illustrative: Year-1 federal savings at the representative rate for each type, 20% land allocation, 100% bonus depreciation, 37% federal bracket. Study cost is current Cost Seg Smart pricing for the price tier.
The percentages sit close together, and your own property can land anywhere in its type’s range. The absolute Year-1 dollar amount keeps climbing with basis.
Free preliminary depreciation estimate — property summary, basis allocation, five-year schedule. We do the work; you get the PDF.
See my estimated Year-1 savings →Order your duplex study
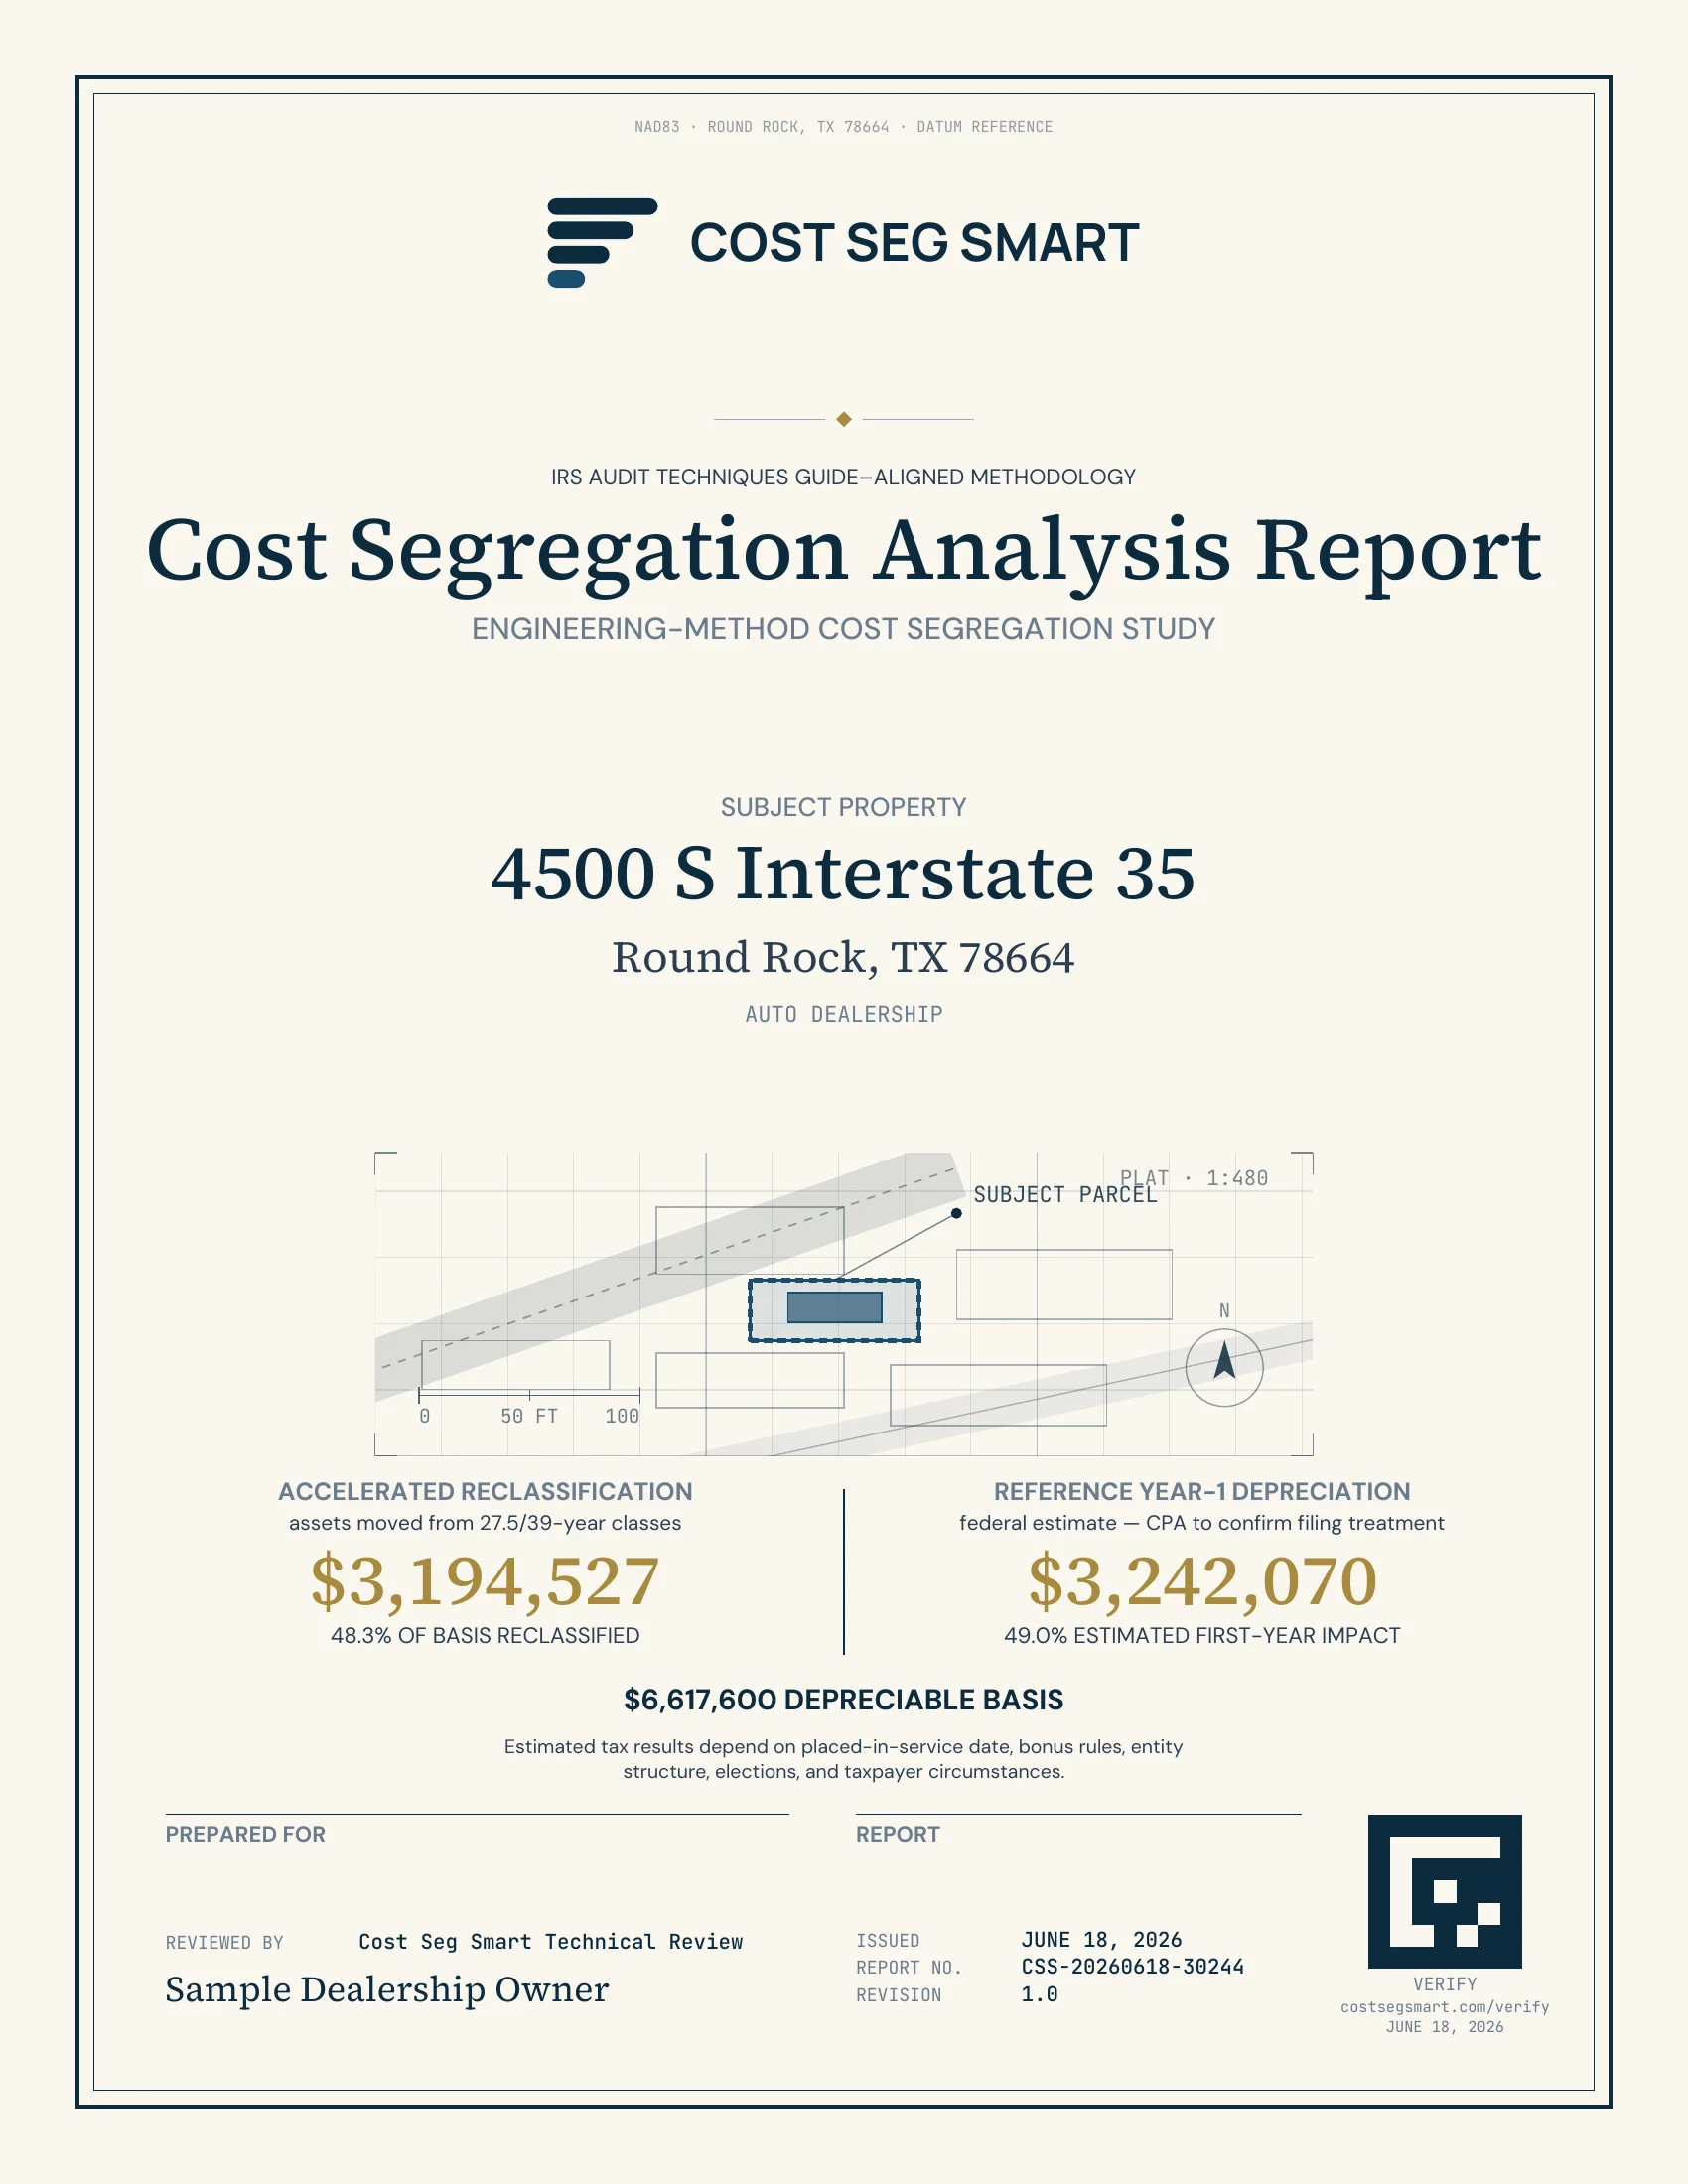
If the math above looks like it fits your situation, your study is delivered in 1–2 business days, with full audit-support scope and a CPA-Ready Guarantee. Remote for most residential and small-commercial studies; on-site observation for larger commercial projects, no email gate to see what you’ll receive — the sample duplex report is open-access.
For a different property type or a duplex you bought before 2025 (Form 3115 lookback case), the order form lets you flag both. Estimated turnaround is the same.
Order your duplex study →
Quality-checked before delivery. 1–2 business day delivery for most residential studies. CPA-Ready Guarantee. Remote for most residential and small-commercial studies; on-site observation for larger commercial projects.
Related guides:
- Multifamily cost segregation guide — covers 2-unit through 100+ unit
- House Hacker’s Duplex: $15K–$40K Year-1 tax savings — owner-occupied duplex specifics
- Sample cost segregation report — see every section of a finished study before you order
- Audit-defense scope — what’s covered if a Cost Seg Smart study is examined
- Reclassification bands by property type — the bands we publish, from delivered studies where measured and modeled elsewhere
Frequently asked
How much will a duplex cost segregation study reclassify?
A duplex typically reclassifies 8–21% of depreciable basis, most often around 15%. For a $400K duplex with 20% land allocation, depreciable basis is $320K and a typical reclassified basis is roughly $48,000 — deductible in Year 1 under 100% bonus depreciation (OBBBA, 2025+). Federal tax savings at a 37% bracket: roughly $17,800. Add state savings of 3–13% depending on conformity.
Is a duplex residential (27.5-year) or commercial (39-year) for depreciation?
Residential. Under IRC §168(e)(2)(A) and Pub. 946, a building qualifies as residential rental property when 80% or more of gross rents come from dwelling units. A duplex with two long-term residential tenants is 100% residential rents and depreciates over 27.5 years — exactly like a single-family rental. Unit count is not the test; tenant use is. This is one of the most common confusions in cost seg conversations with new investors.
How does a duplex compare with a single-family rental?
Per-unit component multiplication. Each dwelling unit has its own kitchen (cabinetry, countertops, appliances — all 5-year personal property), bathroom (fixtures, sometimes specialty plumbing), HVAC (often separated systems for tenant comfort), and flooring (typically separate finish packages), so a duplex study itemizes two of each. The percentages still overlap: a single-family rental typically reclassifies 8–32% of depreciable basis (most often around 15%) and a duplex 8–21% (most often around 15%), because the shell and site grow along with the second unit. What the second unit adds is dollars.
Can I do cost segregation on a duplex I bought years ago?
Yes. File Form 3115 (change of accounting method, automatic consent under Rev. Proc. 2015-13) with your current tax return. The §481(a) catch-up adjustment captures every year of accelerated depreciation you would have taken since the property was placed in service, in one current-year deduction. No amended returns required. For a duplex purchased in 2022 and held three years, that's three years of compounded reclassified depreciation in a single Year-1 deduction.
Will the IRS challenge a cost seg study on a small duplex?
Cost segregation is an IRS-recognized methodology — the IRS publishes a 120-page Audit Techniques Guide (Pub 5653) telling examiners how to evaluate a study, not whether to challenge one. What invites scrutiny is methodology weakness: rule-of-thumb percentages without component basis, missing reconciliation, absent MACRS class citations. A properly executed duplex study — industry-standard 2026 construction cost basis, engineering-grade component schedules, Pub 5653's 13 quality elements — is routine examination posture. See our written audit-defense scope at /audit-defense/ for what's covered if a Cost Seg Smart study is examined.
Does cost segregation pay off on a small duplex under $300K?
Often no. Cost segregation accelerates timing of deductions — it doesn't create new ones. On a $250K duplex with $200K depreciable basis and a typical 15% reclassification, you accelerate roughly $30K into Year 1. At a 32% bracket that's roughly $9,600 in federal tax savings. A $995 Cost Seg Smart study is about a 10× return — usually worth it. A $5,000 traditional firm study with 4–6 week turnaround is the wrong economics at that property size. Below ~$200K depreciable basis, evaluate whether the study fee exceeds 20% of Year-1 federal savings before ordering.