What is a cost segregation study?
A cost segregation study is an engineering-based analysis that allocates the cost of a building to its individual components and assigns each one its IRS depreciation life, so the parts that qualify as 5-, 7- or 15-year property are depreciated faster than the 27.5- or 39-year building around them.
Without a study, IRC §168 depreciates a residential rental over 27.5 years and a commercial building over 39 years as one asset. A study separates out what the IRS classes differently under Rev. Proc. 87-56: appliances, carpet, cabinetry and dedicated wiring as 5-year personal property; paving, fencing, landscaping and site utilities as 15-year land improvements. Those shorter-life classes are eligible for 100% bonus depreciation under §168(k), so the reclassified portion can generally be deducted in the year the property is placed in service.
What you receive: a written report, usually 40+ pages, with the component-by-component cost schedule, the MACRS class and IRS authority for each line, the land and building split, year-by-year depreciation tables and the methodology. Your CPA uses it to report depreciation on Form 4562, or to file Form 3115 for a property placed in service in an earlier year. Read a sample report.
Reviewed by Cost Seg Smart Editorial Team · First published: · Last reviewed: · Sources
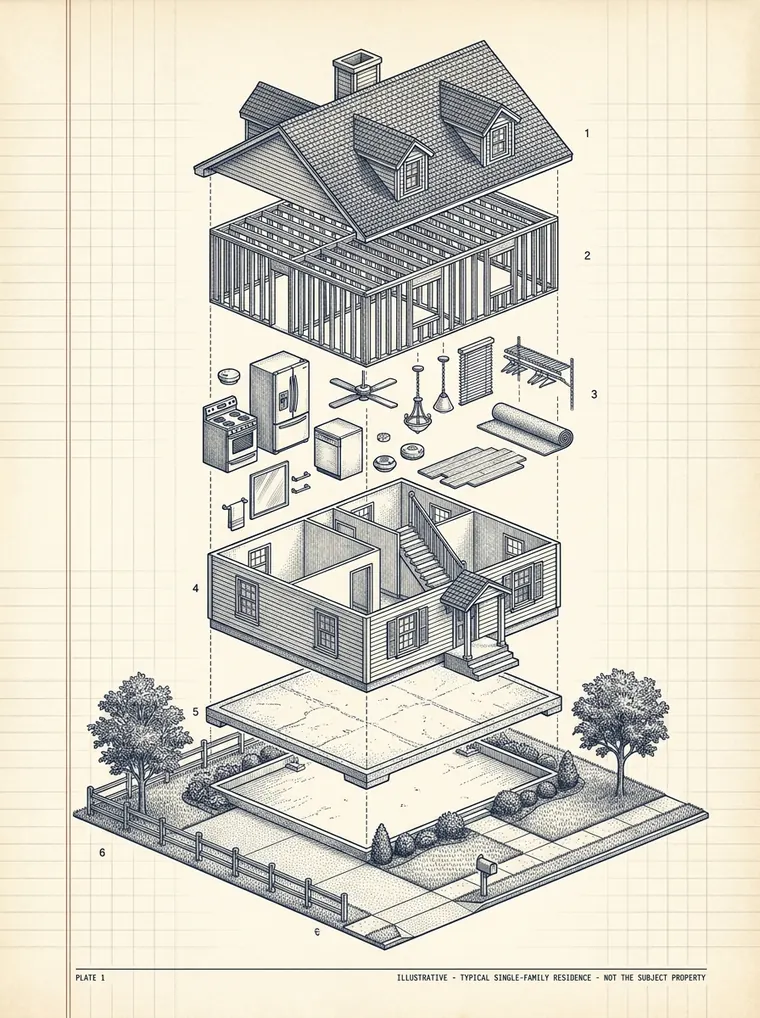
- What it does
- Moves the qualifying share of a building's depreciable basis from the 27.5- or 39-year schedule into 5-, 7- and 15-year classes. Total depreciation over the life of the property is unchanged; the timing moves forward.
- How much moves
- Our published bands: 9–32% of depreciable basis for a single-family rental, 19–39% for a short-term rental, 16–29% for an office building. Finishes, site work, a pool and the land share all affect where a property lands. Estimate yours.
- Who it suits
- Owners of income-producing real estate (rentals, short-term rentals, multifamily, commercial) with taxable income to offset and a hold of a few years or more. Who should, and who shouldn't.
- What it costs
- From $495 for a residential property under $300K, rising with property type and price. Full pricing.
- How long it takes
- Most residential studies are delivered the next business day once your documents are in, and within two business days. Portfolios take one to two business days per property, scheduled with you. Studies with an on-site observation take about a week.
- What you get
- A CPA-ready PDF report. See sample reports (worked examples on modeled properties).
- IRS basis
- IRC §168; Rev. Proc. 87-56 and Pub. 946; the Cost Segregation Audit Techniques Guide (Pub. 5653); Hospital Corporation of America v. Commissioner, 109 T.C. 21 (1997). All sources.
| Also known as | Cost seg, depreciation reclassification study, MACRS reclassification, §481(a) lookback (when applied to prior-year property) |
| Method type | Engineering-based tax accounting analysis; not a property appraisal or inspection |
| Governing statute | IRC §168 (MACRS) · §168(k) (bonus depreciation) · §263A (capitalization) |
| Recovery periods | Per Rev. Proc. 87-56 (class lives reproduced in Pub. 946, Appendix B): 5-yr (personal property), 7-yr, 15-yr (land improvements), 27.5-yr (residential structure), 39-yr (commercial structure) |
| IRS authority | Cost Segregation Audit Techniques Guide (Pub. 5653) defines 13 quality elements an examiner evaluates |
| Mechanism for prior-year property | Form 3115 change in accounting method, claimed as a single-year §481(a) adjustment under Rev. Proc. 2015-13 (automatic-consent) |
| Recapture treatment at sale | §1245 for personal property (ordinary rates, capped at depreciation taken); §1250 for real property (max 25% unrecaptured gain rate); deferable via §1031 exchange |
| Key case law | Hospital Corp. of America v. Commissioner, 109 T.C. 21 (1997) — established the engineering-based reclassification framework. AmeriSouth XXXII v. Commissioner, T.C. Memo. 2012-67 — set documentation standards still cited in IRS examinations. |
| Typical reclassification | 9–32% of depreciable basis on single-family rentals; 19–39% on short-term rentals; 20–37% retail, 16–29% restaurant and office, 15–28% industrial — our published per-property-type modelling assumptions. See the bands by property type, measured on our delivered studies where we have enough of a type. |
| Typical cost | From $495 per study at Cost Seg Smart, scaling with property type and price (pricing); traditional engineering firms commonly quote $5,000–$15,000 |

Watch: cost segregation explained in plain English
Reclassifying parts of your building's basis.
A cost segregation study is an engineering-based analysis that identifies building components eligible for shorter MACRS depreciation lives under Rev. Proc. 87-56. Without a study, the default IRC §168 schedule depreciates residential rental property over 27.5 years and commercial over 39 years. With a study, components like flooring, cabinetry, appliances, site work, and land improvements are reclassified into 5-, 7-, or 15-year recovery periods — and combined with 100% bonus depreciation under §168(k), deducted in full the year the property is placed in service.
The deductions don't change in lifetime total — they accelerate in timing. That's the entire economic value: cash today is worth more than the same dollars spread over 27.5 years. The Tax Court validated this engineering-based reclassification framework in Hospital Corp. of America v. Commissioner, 109 T.C. 21 (1997), and AmeriSouth XXXII v. Commissioner, T.C. Memo. 2012-67, set the documentation standards still cited in IRS examinations today.
For a single-family rental about 9–32% of the depreciable basis can be reclassified into 5- and 15-year MACRS classes, and short-term rentals typically run higher at about 19–39% — accelerating the bulk of depreciation into Year 1 instead of spreading it over 27.5 years.
If you're evaluating whether this applies to your property, you can estimate potential savings in under a minute. Run an estimate →
How a study actually gets built.
Same industry-standard 2026 construction cost basis. Same MACRS framework. Same IRS Audit Techniques Guide methodology a traditional firm uses. The difference is workflow — automation handles the steps that don't change the answer, and our reviewer checks the ones that do.

Property characteristics flow in via the order form: address, purchase price, year built, square footage, property type, and any rehab or improvement basis. That's the full input surface.

The engine pulls county assessor records, RentCast property data, OpenStreetMap building type and landuse, and satellite imagery. Cross-verifies square footage, year built, and finish quality before any cost work begins.

industry-standard 2026 construction cost library is filtered to your property type's component mix — foundation, framing, roofing, HVAC, plumbing, electrical, finishes, FF&E, site work, landscaping. Geo cost multipliers, quality tier, age, and PPI adjustments applied.

Each component is classified to its IRS recovery period — 5-year personal property, 15-year land improvements, 27.5-year residential structure, or 39-year commercial — per the IRS Cost Segregation Audit Techniques Guide. The share that moves depends on property type, condition, improvements and use: our published band is 9–32% of depreciable basis for a single-family rental and 19–39% for a short-term rental.

16-check QC validator runs every study: invariant checks, market regime sanity, calibration outliers, input quality, narrative safety. Result: PASS (ships immediately), REVIEW (our reviewer checks flags), or FAIL (blocks ship).

A 40+ page CPA-ready PDF: executive summary with MACRS pie chart, full component schedule, year-by-year depreciation tables, land valuation methodology, Form 3115 readiness for prior-year lookback. Most residential studies are delivered the next business day once your documents are in, and within two business days. Portfolios take one to two business days per property, scheduled with you. Studies with an on-site observation take about a week.
What a cost segregation study contains.
The deliverable is a PDF report written for the CPA who files your return. A Cost Seg Smart report contains:
- Executive summary: the depreciable basis, how much moved into each recovery class, and the first-year deduction.
- Land and building allocation: how the purchase price was split between non-depreciable land and the building, and the source used.
- Component schedule: every component with its cost, MACRS class, recovery period and the IRS asset class or authority behind the classification.
- Depreciation tables: year-by-year deductions for each class, ready to enter on Form 4562.
- Methodology: data sources, cost basis and the reconciliation of allocated cost to total basis, organized around the IRS Audit Techniques Guide.
- Form 3115 support, when the property was placed in service in an earlier year: the §481(a) catch-up schedule your CPA uses for the accounting-method change.
Read a complete one before ordering: sample cost segregation reports, worked examples built on modeled properties rather than client engagements. If the study is ever examined, the written scope of our support is on our audit support page: we explain our methodology and classifications to your CPA in writing; we do not provide IRS representation.
See what this looks like for your property.
Plug in your purchase price and property type. The calculator uses the same published reclassification bands as this page; on a $500,000 single-family rental the band implies $36K–$125K of Year-1 deductions.
Typical reclassification, by property type.
Range of depreciable basis that typically moves into 5-, 7-, and 15-year MACRS buckets. On a $500,000 single-family rental, the single-family band works out to $36K–$125K of Year-1 deduction.


IRS MACRS depreciation classes.
Every component in your property is classified into one of these recovery periods. Cost segregation moves what's eligible from 27.5/39 into 5/7/15.
How much can you save?
Year-1 deductions vary by property type, purchase price, depreciable basis, and finish level. The ranges below are the band most of our delivered studies fall inside, on the purchase price after a typical land allocation (20% residential, 25% commercial), with 100% bonus depreciation (2025+ rule). Tax savings assume a 37% federal bracket; lower brackets scale proportionally.
Ranges are the low and high of what our delivered studies typically reclassify for each type, not a promise about any one property. Actual results depend on land allocation, finish quality, age of property, and your specific tax situation.
How much does a study cost?
Studies start at $495 for a residential property under $300K. The fee is set by property type and purchase price, because larger and more complex properties have more components to analyze; the first bands of each ladder are below. Every study includes the same methodology, internal technical review and QC, audit support documentation, and Form 3115 readiness for prior-year lookback.
Every band, including the larger properties and the specialty types, is on the pricing page. Several properties at once: portfolio pricing.
Cost Seg Smart delivers engineering-based, fully documented cost segregation reports from $495, with most residential studies delivered the next business day once documents are in, following the IRS Audit Techniques Guide framework.
Why is this so much less than traditional firms?
Most studies are remote; some are not. Whether a study includes an on-site inspection depends on the property — its type, complexity, available documentation, and engagement scope. Most residential and small-commercial studies are completed remotely from primary documentary evidence and reliable secondary data; larger or more complex commercial properties may include an on-site observation. The IRS does not require an on-site inspection (IRS Publication 5653), so a remote study is fully valid where a visit would not change the answer.
We say so up front when a property is a poor fit for our workflow, rather than ship a study we would not stand behind. How the remote and on-site paths differ: remote cost segregation and on-site studies.
Who should get a study, and who shouldn't.
Cost segregation works for almost any income-producing real estate, but the economic benefit is highly dependent on your tax situation, your investment horizon, and how the property is used. Here's where the math is clean, and where it isn't.
By property type: single-family rentals · short-term rentals · multifamily · commercial · office · industrial · renovations · new construction.
- Residential, short-term rental, multifamily or commercial property you rent out or use in a business
- Held now (or planned to hold 2+ years)
- Owner has passive income, qualifies as REPS, or materially participates in an STR
- Placed in service in a prior tax year (a Form 3115 lookback applies)
- High-income taxpayer (24%+ federal bracket — savings scale with bracket)
- Owner-occupied primary residences (not income-producing, so not depreciable)
- Properties under ~$200K — study cost vs. savings doesn't pencil
- Selling within 12 months without a 1031 exchange — recapture eats most of the benefit
- Already deducted full basis under Section 179
- Low marginal bracket where the time-value benefit is smaller
100% bonus depreciation, restored permanently.
Bonus depreciation lets you deduct 100% of qualifying property (5-, 7-, and 15-year MACRS classes) in the first year, instead of spreading it over the recovery period. After phasing down to 60% in 2024, the One Big Beautiful Bill Act (OBBBA, signed July 2025) permanently restored the 100% rate for 2025 and beyond.
For cost segregation, that's the entire point. Every dollar reclassified from 27.5/39-year structure into 5/7/15-year personal property and land improvements is now fully deductible the year placed in service.
IRS basis and audit support.
Cost segregation rests on the MACRS rules in IRC §168, the asset class lives in Rev. Proc. 87-56 (reproduced in IRS Publication 946, Appendix B), and the IRS's own Cost Segregation Audit Techniques Guide (Publication 5653), which describes for examiners what a quality study contains. The Tax Court accepted component-level allocation in Hospital Corporation of America v. Commissioner, 109 T.C. 21 (1997), holding that building components qualifying as tangible personal property under the former investment tax credit rules may be depreciated as §1245 property.
Together with AmeriSouth XXXII v. Commissioner, T.C. Memo. 2012-67, those authorities established that cost segregation requires component-level engineering analysis (not formulaic rules) and defensible cost basis (industry-standard cost data, contractor invoices, or equivalent). A spreadsheet with rule-of-thumb percentages is not a study.
The 13 principal elements of a quality cost segregation study (per the IRS ATG) +
- Preparation by an individual with expertise and experience
- Detailed description of the methodology
- Use of appropriate documentation
- Interviews conducted with appropriate parties
- Use of a common nomenclature
- Use of a standard numbering system
- Explanation of the legal analysis
- Determination of unit costs and engineering "take-offs"
- Organization of assets into lists or groups
- Reconciliation of total allocated costs to total actual costs
- Explanation of the treatment of indirect costs
- Identification and listing of Section 1245 property
- Consideration of related aspects (e.g., depreciation recapture)
Our report's methodology section, component schedule, cost basis and reconciliation are organized around these elements. How each one is addressed, and the written scope of our audit support, is on our audit support page.
Already own the property? Form 3115 lookback.
You don't need to do cost segregation in the year you buy. If you've owned the property for 2+ years and have been taking straight-line depreciation, you can run a lookback study and claim every dollar of missed accelerated depreciation in one shot — no amended returns required.
The mechanism is Form 3115 (Application for Change in Accounting Method), filed with your current-year return. The §481(a) catch-up adjustment puts the entire missed deduction onto this year's return as if you'd done the study from day one.
When a lookback applies, your Cost Seg Smart report includes the §481(a) catch-up schedule and supporting workpapers — your CPA prepares, signs, and files Form 3115 with your return. This is often the easiest cost-seg sale a CPA makes: the client has been overpaying for years and the lookback rebates that overpayment in a single year.
Deeper detail on the mechanics and timing: our Form 3115 and §481(a) guide →
A Form 3115 lookback study lets a property owner catch up every dollar of missed accelerated depreciation in a single tax year — no amended returns, no penalty, recognized as a §481(a) accounting-method change.
Frequently asked questions.
What is a cost segregation study? +
A cost segregation study is an engineering-based analysis of a building's cost that identifies the components which qualify for shorter IRS depreciation lives: 5- and 7-year personal property (appliances, carpet, cabinetry, dedicated electrical) and 15-year land improvements (paving, fencing, landscaping, site utilities). Everything else stays on the 27.5-year residential or 39-year commercial schedule. The output is a written report that allocates the depreciable basis to each component and recovery class, which your CPA uses to report depreciation on Form 4562, or to file Form 3115 when the property was placed in service in an earlier year.
What does a cost segregation study include? +
A Cost Seg Smart report includes an executive summary of the reclassification, the component-by-component cost schedule with the MACRS class and IRS authority for each line, the land and building allocation and how it was derived, year-by-year depreciation tables, the methodology narrative organized around the IRS Audit Techniques Guide, and, where a prior-year property needs a catch-up, the §481(a) schedule your CPA uses for Form 3115. You can read a complete one before ordering: see the sample cost segregation reports (worked examples on modeled properties).
How long does a cost segregation study take? +
Most residential studies are delivered the next business day once your documents are in, and within two business days. Portfolios take one to two business days per property, scheduled with you. Studies with an on-site observation take about a week. Traditional engineering firms commonly quote several weeks.
What is cost segregation in simple terms? +
Cost segregation is the IRS-recognized engineering-based method of breaking a real estate purchase into separate components — flooring, cabinetry, appliances, site work, land improvements — and depreciating each component over its actual useful life (5, 7, or 15 years) instead of the default 27.5 years (residential) or 39 years (commercial). The shorter depreciation lives, combined with 100% bonus depreciation under IRC §168(k), let an investor claim most of the building's depreciation in the first year of ownership instead of spreading it across decades.
What is the purpose of a cost segregation study? +
The purpose is to accelerate depreciation deductions by identifying which parts of a building qualify for shorter MACRS recovery periods under Rev. Proc. 87-56. The deductions don't change in lifetime total — they accelerate in timing. The economic value is the time value of money: a $30K deduction this year is worth more than $30K spread over 27.5 years, especially at high marginal tax rates. The IRS Cost Segregation Audit Techniques Guide (Pub. 5653) defines the methodology examiners use to evaluate these studies.
Is cost segregation worth it? +
Cost segregation is generally worth it when (1) the property is held three or more years, (2) the owner has taxable income meaningful enough to absorb the accelerated deductions, and (3) the depreciable basis exceeds roughly $200,000. On a $500,000 single-family rental our published band implies $36K–$125K of Year-1 deductions, or $13K–$47K of federal tax savings at a 37% bracket; the study fee at that price is $895. Your bracket, land share and the property's finishes all affect where in that range you land. It's not worth it when the property will be sold within 12 months without a §1031 exchange, or when the owner has no taxable income to offset.
Who can benefit from cost segregation? +
Owners of any income-producing real estate — single-family rentals, short-term rentals (Airbnb, VRBO), multifamily, office, retail, restaurant, industrial, medical office, mixed-use. STR owners with material participation under Treas. Reg. §1.469-1T(e)(3)(ii) and real estate professionals (REPS) qualifying under IRC §469(c)(7) can apply the accelerated losses against W-2 or business income. Long-term rental owners typically apply the deductions against passive rental income or carry forward suspended losses under §469.
How much does a cost segregation study cost? +
Cost Seg Smart studies are priced by property type and purchase price: single-family, short-term rental and condo studies start at $495 (under $300K), duplex to fourplex at $995, standard commercial and multifamily 5+ at $995, industrial and self-storage at $2,495, and medical, restaurant and other specialty commercial at $2,995. The fee rises with purchase price; the full matrix is on the pricing page. Traditional engineering firms commonly quote $5,000–$15,000. The difference is mostly workflow: whether a study includes an on-site inspection depends on the property — its type, complexity, available documentation, and engagement scope. Most residential and small-commercial studies are completed remotely from primary documentary evidence and reliable secondary data; larger or more complex commercial properties may include an on-site observation. The IRS does not require an on-site inspection (IRS Publication 5653), so a remote study is fully valid where a visit would not change the answer. See the full pricing matrix.
Can you do cost segregation on a property you already own? +
Yes — this is called a lookback or §481(a) catch-up study. You file IRS Form 3115 (Application for Change in Accounting Method) with your current-year return and claim every dollar of missed accelerated depreciation in a single year. No amended returns are required, and your report includes the §481(a) schedule your CPA uses for the form (see our Form 3115 guide). This is an automatic-consent change under Rev. Proc. 2015-13, with no statute-of-limitations cap — you can reach back to the year the property was placed in service.
What types of property qualify for cost segregation? +
Any depreciable real property placed in service after 1986 qualifies under IRC §168, including single-family rentals, short-term rentals, multifamily (duplex, triplex, fourplex, MF 5+), office, retail, restaurant, industrial, medical office, mixed-use, and self-storage. Owner-occupied primary residences do not qualify because they are not income-producing. Land itself does not qualify (land is not depreciable), but land improvements — driveways, fencing, landscaping, sidewalks — qualify as 15-year property.
Is cost segregation a one-time deduction? +
No. Cost segregation reclassifies basis into shorter MACRS recovery periods that produce annual depreciation deductions over each component's recovery life — 5, 7, or 15 years. Combined with §168(k) bonus depreciation, the bulk of the reclassified basis is deductible in Year 1, but the residual continues to depreciate annually until each component is fully recovered. The 27.5- or 39-year residential/commercial structure portion continues on its standard schedule alongside.
How do you produce an engineered study without a site visit? +
An engineering-based cost segregation study is an analysis of building components and their depreciation lives — not a physical inspection. The IRS Audit Techniques Guide does not require an on-site visit; it requires that components be classified using engineering principles and a defensible cost basis. We use county assessor records, RentCast property data, OpenStreetMap, and satellite imagery to characterize the property, and the industry-standard 2026 construction cost library to value its components. The same inputs an on-site engineer would record on a clipboard.
What if my property is unusual? +
Our QC gate flags unusual properties — distressed pricing, atypical mix, very large multifamily, complex commercial — and routes them to internal technical review before anything ships. If a property is a poor fit for our automated workflow (e.g., a $25M mixed-use complex with multiple parcels), we'll tell you up front and refer you to a traditional engineering firm. We don't ship studies we can't stand behind.
Does the IRS accept your reports? +
Cost segregation is a recognized tax strategy under IRS Revenue Procedure 87-56 and the Cost Segregation Audit Techniques Guide. Our reports follow the same MACRS framework, the same component-level detail, and the same documentation standards as any engineered study. The deliverable includes the methodology section, data sources, component schedule, and internal technical review & QC that a CPA needs to file Form 3115 (for prior-year lookback) or report current-year depreciation.
What happens if my study gets audited? +
The report itself is the documentation an examiner asks for: methodology, data sources, and every component's classification with its IRS basis. If the study is examined, your CPA can send us technical questions in writing and we explain our methodology and classifications, at no additional charge, for the life of the study. Your CPA owns the examination and drafts the response; we do not provide IRS representation, which under Circular 230 belongs to a CPA, EA or attorney. The full written scope is on our audit support page.
Does cost segregation still make sense with 100% bonus depreciation back in 2025? +
Yes — more so than during the 60–80% phase-down years. With 100% bonus depreciation permanently restored under OBBBA (signed July 2025), every dollar reclassified into 5-, 7-, or 15-year MACRS property is fully deductible in Year 1. That's the whole point of cost segregation: maximize what gets reclassified into bonus-eligible buckets so the full first-year deduction is as large as possible.
What about depreciation recapture if I sell? +
Depreciation recapture applies whether you do cost segregation or not — the IRS recaptures depreciation actually taken (or that you should have taken) on sale. Cost seg accelerates the timing of deductions but doesn't change the lifetime total. The benefit is the time value of money: a $30K deduction this year is worth more than $30K spread over 27.5 years. If you sell in 1–2 years, the recapture math may eat most of the benefit; that's why our buyer-fit guidance flags 'selling within 12 months without a 1031' as a poor fit.
Does cost segregation increase my audit risk? +
Engineering-based studies that follow the IRS Cost Segregation Audit Techniques Guide are not a high-audit-risk strategy. Risk increases with poorly documented studies (DIY spreadsheets, no cited methodology, no component-level basis) — which is why we deliver a 40+ page report with cited methodology, industry-standard construction cost basis per component, and internal technical review & QC. We've covered the documentation standards Hospital Corp v. Commissioner and the AmeriSouth REIT cases established as the bar. For our written audit-support scope and the 13 IRS Pub. 5653 quality elements an examiner evaluates, see /audit-defense/.
Do I need to qualify as a Real Estate Professional (REPS) to benefit? +
No. REPS status determines whether you can use rental losses against active income (W-2, business income), but cost segregation creates depreciation regardless of REPS. Most STR owners use the short-term rental loophole — Treas. Reg. §1.469-1T(e)(3)(ii)(A), the 'average customer use 7 days or less' rule — to treat losses as non-passive without REPS, then qualify for material participation under one of the seven §1.469-5T tests. How to qualify your hours. Long-term rental owners typically use cost-seg deductions against passive rental income or carry forward suspended losses.
Can I do cost segregation on multiple properties at once? +
Yes. Each property gets its own study, but the workflow is identical and you can order in batches. Many CPAs and portfolio investors run cost seg on 5–20 properties in a single tax year. If your CPA is filing a consolidated return, having all studies follow the same methodology and reporting format (which ours do) makes their work simpler.
Sources & primary references.
The tax-treatment statements on this page rest on the primary sources below. Cost Seg Smart studies are prepared under this framework.
- IRS Cost Segregation Audit Techniques Guide (Pub. 5653) — the canonical IRS framework defining methodology, evidentiary standards, and the 13 quality-control elements every defensible study must address.
- IRS Pub. 946 — How to Depreciate Property — MACRS recovery periods, conventions, and depreciation tables underlying every component classification.
- Rev. Proc. 87-56, 1987-2 C.B. 674 — Asset Class Lives — assigns each asset class its class life and MACRS recovery period; the table is reproduced in Pub. 946, Appendix B.
- IRS Form 3115 — Application for Change in Accounting Method — the mechanism for §481(a) lookback adjustments on properties already placed in service.
- 26 U.S.C. §168 — Accelerated Cost Recovery System (MACRS) — governs MACRS recovery periods + §168(k) bonus depreciation; the statutory basis for cost segregation reclassification.
- 26 U.S.C. §263A — Capitalization Rules (UNICAP) — capitalization rules for indirect costs; relevant where cost-seg classifications affect basis at acquisition.
- 26 U.S.C. §481(a) — Adjustments Required by Changes in Method of Accounting — the statute that permits lookback catch-up adjustments via Form 3115 without amending prior returns.
- Hospital Corporation of America v. Commissioner, 109 T.C. 21 (1997) — the Tax Court held that building components qualifying as tangible personal property under the former investment tax credit rules may be depreciated as §1245 property, the foundation of component-level cost segregation.
- AmeriSouth XXXII, Ltd. v. Commissioner, T.C. Memo. 2012-67 — Tax Court memo setting documentation standards still cited in IRS cost-segregation examinations.
- Rev. Proc. 2015-13 — Automatic Consent for Method Changes — establishes that depreciation method changes (DCN 7) for cost-seg lookback are automatic-consent, requiring no IRS pre-approval.
- One Big Beautiful Bill Act (OBBBA, July 2025) — permanently restored 100% bonus depreciation under §168(k) for property placed in service in 2025 and beyond.
- Industry-Standard Construction Cost Data — industry-standard component-level cost basis used in every Cost Seg Smart study, indexed to local market multipliers.
- Treas. Reg. §1.469-1T — material participation rules + the §469(c)(7) STR exception (7-day average rule for short-term rentals).
- Cost Seg Smart reclassification bands by property type — the source for percentage ranges quoted on this page; measured on our delivered studies where we have enough of a property type, modeled elsewhere.
What an examiner evaluates, and exactly what our audit support covers and does not: audit support scope. The case-law timeline: cost segregation legal history.
If you're considering a cost segregation study, the next step is usually to estimate potential savings based on your property.
Run an estimate → · Order a study →
From $495 · Most residential studies the next business day · Free revisions, then a refund if your CPA still can't use it.