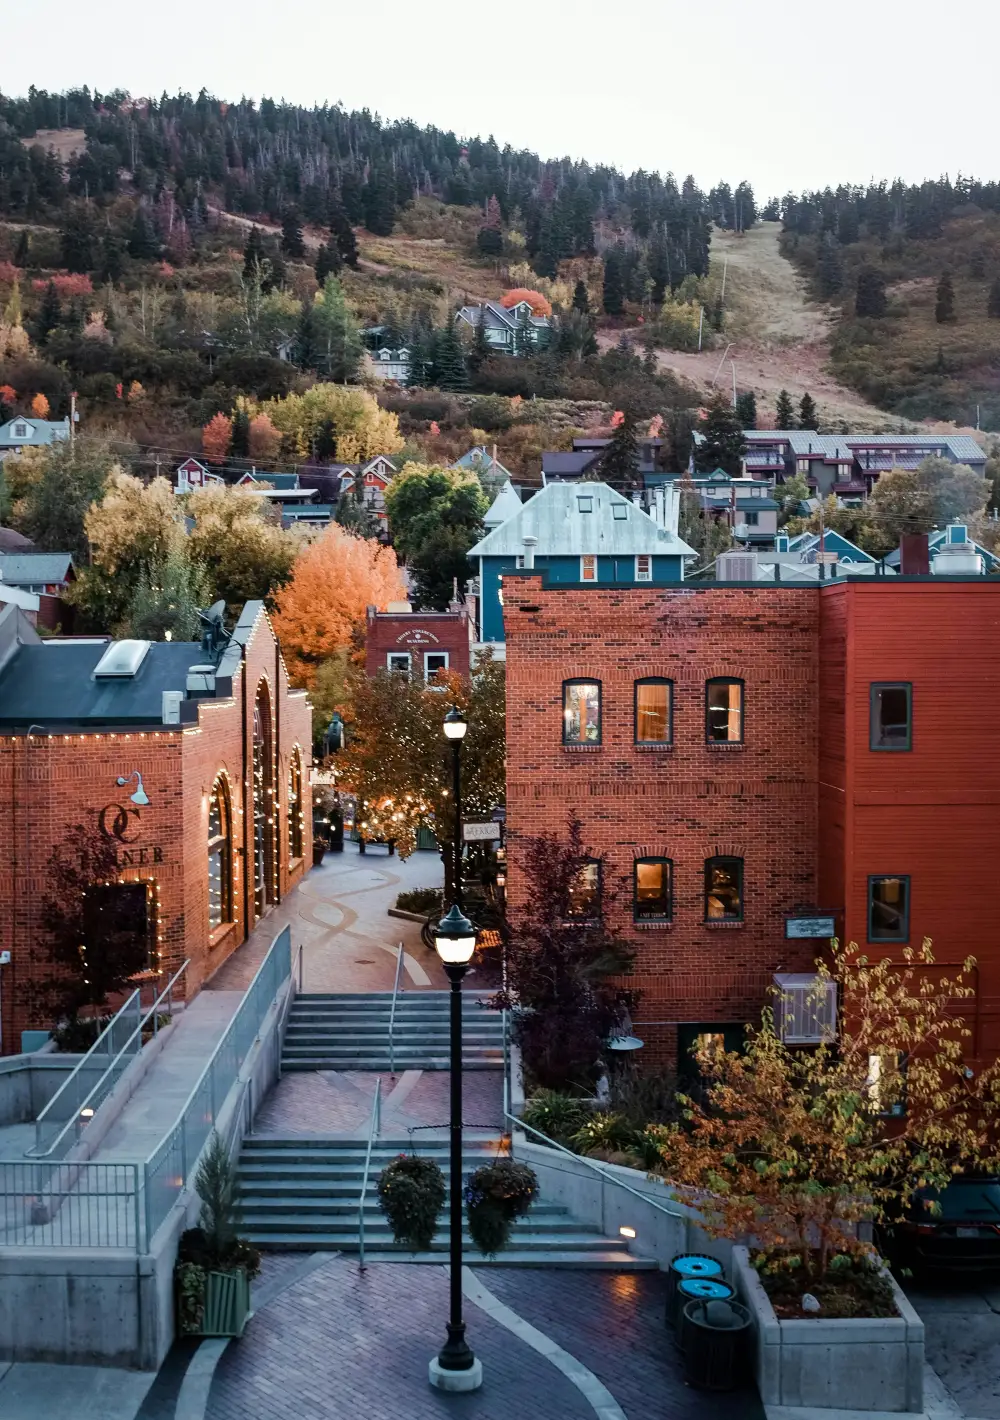
Utah pairs one of the country’s deepest ski short-term rental markets with a fast-growing tech economy and a desert vacation-home market in the south. Park City, Deer Valley and the Cottonwood Canyons anchor a high-furnishing vacation-rental economy where seven-figure basis is common; Salt Lake City and the Silicon Slopes corridor (Lehi, Draper, Provo) drive furnished mid-term demand from a large tech workforce; St. George and the Zion gateway towns add pool-and-casita vacation homes. For the state return, the story is simpler than in most states: Utah conforms to federal bonus depreciation and taxes individual income at a single flat rate. See Your Utah Tax Savings →
- IRS Audit Techniques Guide methodology
- 40+ page CPA-ready report
- Delivered in 1–2 business days for simple residential
- Audit support included, and if the IRS questions methodology we respond directly at no extra charge
- Every report is quality-checked before delivery
Utah conforms to federal bonus depreciation
Utah defines “the Code” as the Internal Revenue Code in effect for the taxable year, by rolling reference, for both the individual income tax (Utah Code §59-10-103) and the corporate franchise and income tax (§59-7-101). The statute that lists Utah’s additions to and subtractions from federal income (§59-10-114) has no depreciation or §168(k) entry. In practice that means the first-year deduction your federal return takes from a cost segregation study generally flows straight into Utah taxable income, with no separate Utah depreciation schedule to track and no add-back to reverse in later years. The state-by-state detail, with citations, is on our Utah bonus depreciation page.
Not every state works this way. Several states decouple from federal bonus depreciation and require a separate, slower state depreciation schedule, so the Year-1 deduction shrinks on the state return; Nevada and Wyoming next door have no individual income tax at all. Our state-by-state conformity table lists each. A Utah owner gets the same acceleration on both returns.
Utah’s flat rate: 4.45% for 2026
Utah taxes resident individual income at a single flat rate, set in Utah Code §59-10-104. The 2026 General Session lowered it to 4.45% for taxable years beginning on or after January 1, 2026, continuing a string of cuts over the past several sessions. Because there are no brackets, the state value of an extra dollar of deduction is the same for every Utah filer: about 4.45 cents, if the loss is usable in that year.
On the Park City example below, the $175,000 reclassified would be worth roughly $7,800 on the Utah return at 4.45%, on top of the federal figure, provided the owner can use the loss in the year. Whether the loss is usable is a passive-activity question (below), not a conformity one. Your CPA confirms both.
How Cost Segregation Works in Utah
A study splits a Utah rental’s building basis into 5-year (furnishings, appliances, carpet, decorative lighting), 7-year and 15-year (paving, fencing, landscaping, pools and other land improvements) recovery classes, with the remainder left on the 27.5-year residential or 39-year commercial schedule. Components in the shorter classes are eligible for federal bonus depreciation in the year the property is placed in service, and in Utah that acceleration carries to the state return too.
At the federal level, every $100K reclassified produces about $37K of Year-1 federal tax savings at the 37% bracket; Utah’s 4.45% adds about $4.5K more when the deduction is usable, for a combined rate a little above 41%.
Worked example (illustrative figures) — $850K Park City ski STR:
- $850,000 purchase price
- $680,000 depreciable basis (excluding land)
- $175,000 accelerated depreciation (reclassified to 5/7/15-year MACRS)
- ~$64,750 estimated federal tax savings (37% bracket)
- ~$7,800 more on the Utah return at the 4.45% flat rate, if the loss is usable this year
Representative Utah Year-1 federal savings: $30,000 – $110,000 depending on basis and property type.
Park City and Deer Valley ski rentals
Park City is where Utah’s largest cost segregation deductions come from, because a ski rental is furnished to a standard a long-term rental never is. A typical ski-in/ski-out condo or mountain home near Park City Mountain or Deer Valley carries a full furniture package, ski and boot storage, boot dryers, a gas fireplace insert, hot tub, game-room equipment and a commercial-grade washer and dryer for turnover laundry. Those items tend to land in the 5-year class, and the heavier the furnishing package, the larger the share of basis a study moves out of the 27.5-year schedule. Our Park City cost segregation guide walks through a ski condo component by component.
Three things are specific to this market:
- Condo-hotel and HOA buildings. Much of the Park City rental stock sits in buildings with shared lobbies, pools, spas, ski lockers and parking. A study allocates the owner’s share of those common elements and carves out what the owner does not own, so the unit’s reclassified basis is not overstated.
- Professional management. Many Park City owners use a full-service manager. That is convenient but it complicates the short-term-rental material participation test, which generally asks whether you spent 100 or more hours on the rental and more than anyone else, including the manager’s staff. A study sizes the deduction; your hours decide whether it can offset W-2 or business income this year or carries forward.
- Nightly rental licensing. Park City and surrounding Summit and Wasatch County jurisdictions regulate nightly rentals, and a property’s permitted use can change what it earns and how it is operated. Check local licensing before you close; it does not change the cost segregation math, but it can change whether the property operates as a short-term rental at all.
Salt Lake City and Silicon Slopes rentals
The Wasatch Front market is a different investor profile. Salt Lake City, Draper, Lehi and Provo rentals are more often single-family homes, townhomes and small multifamily bought by people with high W-2 income from the tech, healthcare and university employers along the corridor. Much of the housing along I-15 is newer construction, which documents cleanly for a study: builders’ specification sheets, finish selections and appliance packages make the component schedule easier to support.
For this profile the planning question is usually timing. A large equity-compensation year, such as an RSU vest or an exit, is exactly when an accelerated deduction is most valuable, but only if the loss is non-passive: through the short-term rental material participation route (average stays of seven days or less, with your own hours) or through real estate professional status. A long-term unfurnished rental owned by a full-time employee usually produces a passive loss that carries forward rather than offsetting salary. Furnished mid-term rentals of 30 days or more generally sit outside the short-term rental exception, so their losses follow the ordinary passive rules. Our Salt Lake City and Provo & Lehi pages cover each market in more detail.
St. George and southern Utah vacation homes
Washington County, from St. George to the Zion gateway towns, is Utah’s second vacation-rental market, built around warm winters, golf and national-park traffic. Properties here are more often single-family vacation homes with a private pool, spa, outdoor kitchen, pergolas and a casita. Pools, decks, hardscape and site improvements are generally 15-year land improvements, and outdoor furnishings are generally 5-year property, so a well-equipped desert rental can reclassify a share of basis comparable to a ski condo even without the ski-specific items.
Utah portfolios and Form 3115 lookback
A common Utah portfolio is a Park City ski rental, a Wasatch Front long-term rental and, increasingly, a southern Utah vacation home. Properties bought during the 2020–2023 run-up that never had a study can still claim the missed depreciation: a Form 3115 accounting-method change takes it as a single §481(a) adjustment on the current federal return, and because Utah conforms, that adjustment generally carries to the Utah return as well. Owners ordering several properties together get a bundle discount. See bundle pricing →
Key Markets in Utah
Park City, UT
Utah’s premier resort market. Ski-in/ski-out condos and mountain homes serving Park City Mountain and Deer Valley carry the heaviest FF&E in the state, with basis routinely $1M+. The highest absolute first-year deductions in Utah. See Park City breakdown →
Salt Lake City, UT
The state’s economic hub. A mix of SFR rentals, downtown condos, and furnished MTRs serving the tech, healthcare, and university workforce. Median rental basis runs $500K–$900K. See Salt Lake City breakdown →
Provo & Lehi, UT
The heart of Silicon Slopes. Tech-employer growth in Lehi, Draper, and Provo (plus BYU and UVU) drives furnished MTR and SFR demand. Newer construction documents well for precise engineering analysis. See Provo / Lehi breakdown →
Which Utah rentals are the strongest candidates
Usually a strong fit:
- A furnished Park City, Deer Valley or Cottonwood Canyons ski rental above roughly $400K, where you (not only a manager) put in the hours
- A southern Utah vacation home with a pool, outdoor living areas and a full furniture package
- A Wasatch Front rental owned by a real estate professional, or a year with enough passive income to absorb the loss
- Any Utah rental placed in service in the last few years without a study, through Form 3115
Often a weaker fit:
- A long-term unfurnished rental under about $300K owned by a full-time employee with no passive income, where the loss would simply carry forward
- A property you expect to sell within a year or two, since depreciation recapture applies at sale (up to 25% on the real-property portion and ordinary rates on some personal property)
Cost Segregation by City in Utah
Opportunities vary by market. Select a city below to see estimated savings and a detailed MACRS breakdown.
Park City, UT
Median STR: $1,200,000 · ~$45,000–$110,000 Year-1 federal savings · See Park City breakdown →
Salt Lake City, UT
Median rental: $650,000 · ~$26,000–$70,000 Year-1 federal savings · See Salt Lake City breakdown →
Provo & Lehi, UT
Median rental: $600,000 · ~$24,000–$65,000 Year-1 federal savings · See Provo / Lehi breakdown →
Utah Cost Segregation Guides
- Park City, UT cost segregation guide
- Utah bonus depreciation conformity
- Short-Term Rental Cost Segregation
- Single-Family Rental Cost Segregation
- Cost Segregation Calculator
- See a sample cost segregation report
- Short-term rental material participation test
See Your Estimated Utah Savings
Run your numbers in under 30 seconds, then take the Year-1 federal figure and add roughly 4.45% of the deduction for Utah if the loss is usable this year. Your CPA confirms the state-side treatment before filing. See Your Utah Tax Savings →
CPA use note: These figures estimate the size of the depreciation deduction. Whether the loss is usable in the current year depends on passive-activity rules, STR material participation, REPS status, entity structure, depreciable basis, and state conformity. Your CPA decides how and when it is applied. Specialty and site components (equipment, casework, docks, pools, arenas, tenant improvements, and similar) are only classified when you own them and they are included in the depreciable basis being studied.
How should Utah investors choose a cost segregation provider?
For an Utah investor buying a property in the $850,000 range, the choice of provider is a major controllable variable in the return. The IRS Audit Techniques Guide sets the quality characteristics an engineering-based study should meet — industry-standard construction cost data, MACRS classification, and component-level documentation — but it does not make every provider's work identical; rigor, cost, and turnaround still vary.
Traditional engineering studies often run several thousand dollars and can take several weeks, because they include on-site inspections, sales discovery calls, and scheduling overhead. The IRS Cost Segregation Audit Techniques Guide does not prescribe an on-site inspection as a standalone requirement; it sets out the quality characteristics of an engineering-based study — component-level classification, a documented and supportable cost derivation, and a clear audit trail — and describes how a physical inspection can contribute to meeting them.
Modern automated providers (such as Cost Seg Smart) deliver an engineering-based, IRS ATG-aligned study using property records, documents, photos, and recognized construction-cost data, typically from $495 and often within 1–2 business days. For an Utah investor at a high combined bracket, that cost and speed difference is meaningful. The CPA-Ready Guarantee (free revisions if your CPA flags a problem, and a refund if the report still can't be used) makes the decision essentially risk-free on the report itself.
The automated path is best-fit for owners who can provide closing documents and property photos online (no in-person visit required) and want the report in time to file the current year's return rather than the next one.
All Cost Seg Smart studies include the CPA-Ready Guarantee (free revisions if your CPA flags a problem, and a refund if the report still can't be used). Straightforward residential studies are often delivered in 1–2 business days and completed remotely; larger or more complex commercial studies take longer and may include an on-site observation.